Best PayPal alternatives in 2026: 8 Compared

- Stripe is our pick for businesses that need online payments with strong developer tools.
- Wise suits international transfers and multi-currency accounts, with transparent fees.
- Square is best for small businesses that sell in person and online.
- Venmo suits friends and family payments in the US, with a social feed.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
 Stripe | Online businesses | See website | No | Visit |
 Square | Small sellers | See website | No | Visit |
 Wise | International transfers | See website | No | Visit |
 Venmo | US friends and family | Free | Yes | Visit |
 Cash App | US peer payments | Free | Yes | Visit |
 Skrill | International wallets | See website | No | Visit |
 Payoneer | Freelancers paid internationally | See website | No | Visit |
 Zelle | US bank transfers | Free | Yes | Visit |
The best paypal alternatives
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews to build this list, focusing on products that fit the topic closely and are still available in October 2026.
Stripe
Ideal for: Online businesses

For buyers who want a clear fit, Stripe is aimed at online businesses. Stripe offers online payments with strong developer tools and global reach. Online businesses can build checkouts, subscriptions and invoicing. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The trade-off is worth naming plainly. Technical setup is needed, and fees apply per transaction. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Stripe is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Developer tools
- Online payments
- Global reach
- Technical setup
- Fees per transaction
Square
Ideal for: Small sellers
If that use case sounds familiar, Square is aimed at small businesses. Square combines in-person hardware with online selling for small businesses. Small sellers can take cards in person and online in one account. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
On the other side of that strength, Fees apply per transaction, and account holds can happen. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Square is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- In-person and online selling
- Hardware
- Simple fees
- Fees per transaction
- Account holds can happen
Wise
Ideal for: International transfers
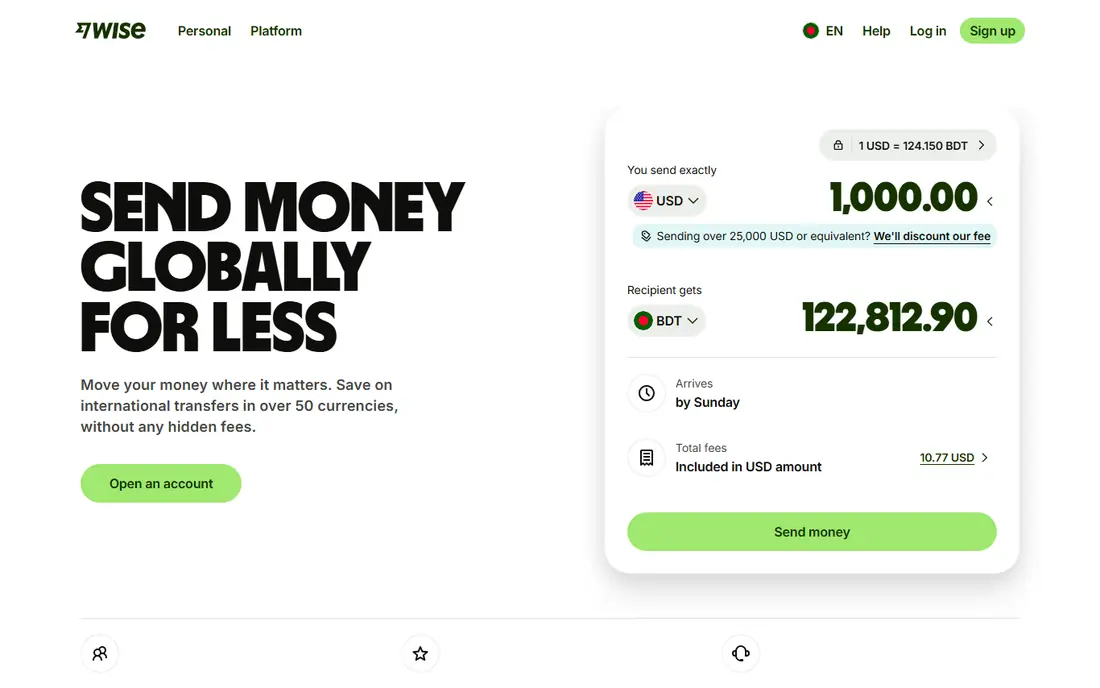
Among the options here, Wise is aimed at international users. Wise offers international transfers with transparent fees and a multi-currency account. International users can hold and send money in many currencies. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
Before you commit, weigh this part. It is not a full bank in all countries, and transfer limits vary. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Wise is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Transparent international fees
- Multi-currency account
- Debit card
- Not a full bank in all countries
- Transfer limits vary
Venmo
Ideal for: US friends and family
For a team or household weighing this choice, Venmo is aimed at US friends. Venmo offers easy peer payments in the US with a social feed. Friends can split bills and send money quickly. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The honest catch comes next. It is US only, and purchase protection is limited compared with PayPal. On price, the starting point listed above is free, and the free plan entry is Yes. If that combination fits your budget and your main use case, Venmo is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Easy US peer payments
- Social feed
- Debit card
- US only
- Purchase protection is limited
Cash App
Ideal for: US peer payments
When the main need is the one above, Cash App is aimed at US peer users. Cash App offers easy US peer payments with a Cash Card and investing features. US users can send money, spend and invest in one app. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
Pricing and limits deserve a second look. It is US and UK only, and instant transfers carry fees. On price, the starting point listed above is free, and the free plan entry is Yes. If that combination fits your budget and your main use case, Cash App is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Easy US payments
- Cash Card
- Investing features
- US and UK only
- Fees for instant transfers
Skrill
Ideal for: International wallets
For readers who put this factor first, Skrill is aimed at international wallet users. Skrill is an international digital wallet with a prepaid card. International users can send money and pay online in many countries. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
A smaller drawback can still matter. Fees vary, and availability varies by country. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Skrill is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- International wallet
- Crypto and gambling payments in some regions
- Prepaid card
- Fees vary
- Availability varies
Payoneer
Ideal for: Freelancers paid internationally
In a crowded field, Payoneer is aimed at international freelancers. Payoneer suits freelancers and businesses paid internationally. It offers multi-currency receiving accounts and mass payouts. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
What to check before paying is simple. Fees vary, and account setup involves checks. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Payoneer is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- International freelancer payments
- Multi-currency
- Mass payouts
- Fees vary
- Account setup checks
Zelle
Ideal for: US bank transfers
For a first purchase in this category, Zelle is aimed at US bank customers. Zelle offers fast, free bank-to-bank transfers in the US. US bank customers can send money directly between bank accounts. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The limit to keep in mind is this. It is US only, offers no purchase protection, and needs a participating bank. On price, the starting point listed above is free, and the free plan entry is Yes. If that combination fits your budget and your main use case, Zelle is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Free US bank-to-bank transfers
- Fast
- Bank integration
- US only
- No purchase protection
- Bank needed
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each product, and we kept only products that are still available in October 2026 and that fit the topic closely. Where a vendor did not publish a clear starting price on its own site, we wrote See website rather than guessing. Prices can change, so check the vendor page linked in each product block before you buy.
Choosing a PayPal alternative that fits how you pay
Start with the job: sending money to friends, selling online, or paying internationally each suit different tools. Check fees for your exact use, since sending, receiving, currency conversion and instant transfer fees differ. Check buyer and seller protection, since not all tools protect purchases the same way. Finally, check availability in your country, since some tools are US-only or limited internationally.
Frequently asked questions
What is the best alternative to PayPal?
Stripe suits online businesses, Wise suits international transfers, Square suits small sellers, and Venmo suits US friends and family payments.
Is Wise cheaper than PayPal for international transfers?
Often, yes, since Wise shows mid-market rates and transparent fees, while PayPal conversion fees can be higher. Compare the total received amount, not just the fee.
Can I use Stripe without a website?
Yes, Stripe offers payment links and invoicing, so small sellers can accept payments without building a checkout.
Is Venmo safe?
Venmo suits friends and family payments, but it is not designed for buyer protection on goods in the same way as PayPal Goods and Services. Use purchase protection options where offered.
What is the best PayPal alternative for business?
Stripe and Square suit most small businesses, while Payoneer suits freelancers paid internationally.