Best ACH Processing Companies in 2026: 7 Options Compared

- Our pick for most people is Stripe, because it is best for payments including ACH debits and covers the core needs well.
- Free options worth trying first include several options offer a free tier or trial.
- Prices and free plans vary widely, so check the vendor pricing page for the plan that matches your use before you pay.
- The best choice depends on how much you use the tool each week and which single feature you cannot do without.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
 Stripe | payments including ACH debits | See website | No | Visit |
 Square | payments with ACH options for businesses | See website | No | Visit |
 Dwolla | ACH payments API for businesses | See website | No | Visit |
 Plaid | bank connections that support ACH | See website | No | Visit |
 GoCardless | direct debit and ACH style payments | See website | No | Visit |
 Authorize.net | payment gateway with eCheck ACH | See website | No | Visit |
 Helcim | payments with ACH and invoicing | See website | No | Visit |
The best ACH processing companies
ACH processing moves money directly between bank accounts, usually at a lower fee than cards, but with slower settlement and return rules to understand. The companies below range from full payment platforms to ACH specialists, so your pick should follow volume, whether you need an API or a dashboard, and how you handle returns and verification.
Stripe
Ideal for: payments including ACH debits
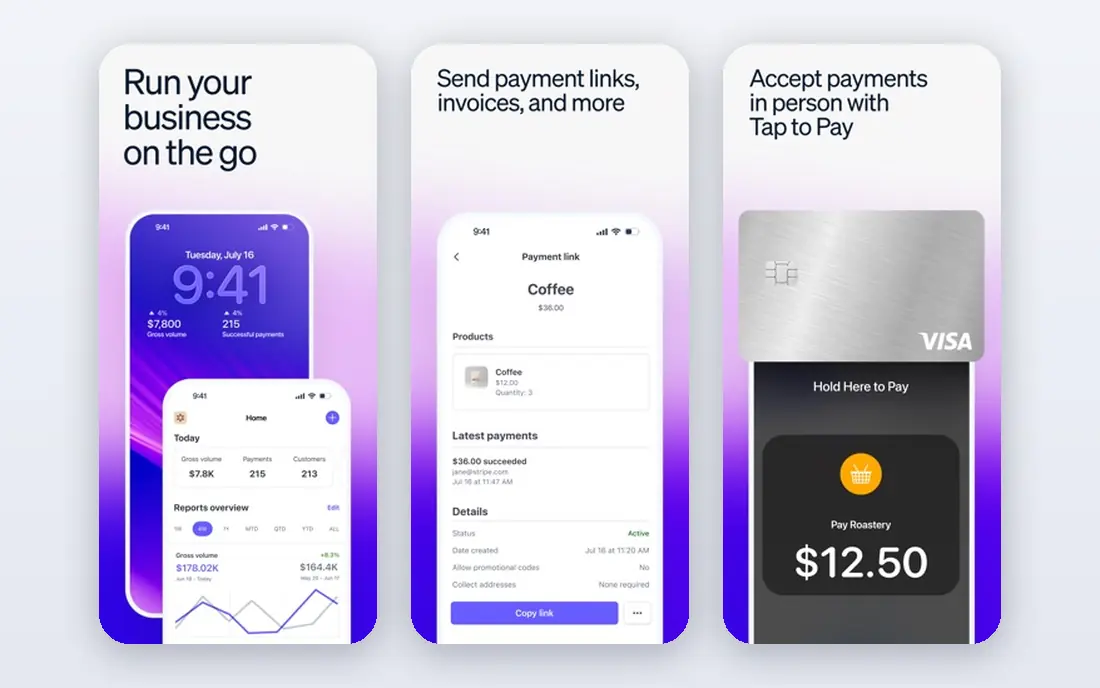
What stands out about Stripe is how well it fits payments including ACH debits. Its strengths include ACH plus cards in one platform and developer tools, which cover the core of what most people need from this kind of tool. On the other side, ACH fees and timing vary, so it is not a perfect fit for everyone. Check the pricing page and the free plan terms before you sign up, since plans change and the details matter more than the headline price.
Our view is that Stripe earns its place through ACH plus cards in one platform, even though account holds can occur keeps it from topping the list. It works best for payments including ACH debits, and readers in that group will get the most from it. Before paying, confirm the plan covers the features you need, and check whether the free plan is enough for a first test.
- ACH plus cards in one platform
- Developer tools
- Wide coverage
- ACH fees and timing vary
- Account holds can occur
Square
Ideal for: payments with ACH options for businesses
In practice, Square suits readers who want payments with ACH options for businesses without a long setup. The honest catch is fees vary, and that is worth testing during any free period or trial. We would still shortlist it, because simple setup is a genuine advantage over several rivals here. Read recent user reviews alongside the official pages, since support quality and small limits often show up there first.
The case for Square rests on simple setup and invoicing. For payments with ACH options for businesses, that combination is hard to ignore, and the official pricing is clear enough to compare with rivals. The weak spot is ACH features are lighter than specialists, which may matter little if you use the tool lightly, and a lot if you push it hard. Try the free option first where one exists, and only upgrade when you hit a limit you actually feel.
- Simple setup
- Invoicing
- Point of sale plus online
- ACH features are lighter than specialists
- Fees vary
Dwolla
Ideal for: ACH payments API for businesses
Our view is that Dwolla earns its place through ACH focused API, even though pricing is quote based keeps it from topping the list. It works best for ACH payments API for businesses, and readers in that group will get the most from it. Before paying, confirm the plan covers the features you need, and check whether the free plan is enough for a first test.
We kept Dwolla on the list because it serves ACH payments API for businesses well, with ACH focused API as its clearest strength. The drawback to note is pricing is quote based. That is the kind of limit that is easy to miss on a marketing page, so we flag it here rather than letting you find it after paying. Compare it directly with the option above it before you decide.
- ACH focused API
- Bank transfers
- Developer docs
- Needs developer work
- Pricing is quote based
Plaid
Ideal for: bank connections that support ACH
The case for Plaid rests on bank account verification and wide bank coverage. For bank connections that support ACH, that combination is hard to ignore, and the official pricing is clear enough to compare with rivals. The weak spot is Plaid is connectivity, not a full processor alone, which may matter little if you use the tool lightly, and a lot if you push it hard. Try the free option first where one exists, and only upgrade when you hit a limit you actually feel.
For most readers, Plaid is the first option worth a close look. It is best for bank connections that support ACH, and its main strengths are bank account verification and wide bank coverage. We compared its official feature pages and pricing with the other options on this list, and it held up well on the points that matter day to day. The trade-off is real too: Plaid is connectivity, not a full processor alone. If that limit touches something you do often, weigh it before you commit.
- Bank account verification
- Wide bank coverage
- Developer tools
- Plaid is connectivity, not a full processor alone
- Pricing varies
GoCardless
Ideal for: direct debit and ACH style payments
We kept GoCardless on the list because it serves direct debit and ACH style payments well, with recurring bank payments as its clearest strength. The drawback to note is fees vary. That is the kind of limit that is easy to miss on a marketing page, so we flag it here rather than letting you find it after paying. Compare it directly with the option above it before you decide.
What stands out about GoCardless is how well it fits direct debit and ACH style payments. Its strengths include recurring bank payments and international coverage, which cover the core of what most people need from this kind of tool. On the other side, US ACH is one part of a wider direct debit tool, so it is not a perfect fit for everyone. Check the pricing page and the free plan terms before you sign up, since plans change and the details matter more than the headline price.
- Recurring bank payments
- International coverage
- Simple dashboard
- US ACH is one part of a wider direct debit tool
- Fees vary
Authorize.net
Ideal for: payment gateway with eCheck ACH
For most readers, Authorize.net is the first option worth a close look. It is best for payment gateway with eCheck ACH, and its main strengths are eCheck ACH support and gateway plus merchant account. We compared its official feature pages and pricing with the other options on this list, and it held up well on the points that matter day to day. The trade-off is real too: monthly fees apply. If that limit touches something you do often, weigh it before you commit.
In practice, Authorize.net suits readers who want payment gateway with eCheck ACH without a long setup. The honest catch is interface feels older, and that is worth testing during any free period or trial. We would still shortlist it, because eCheck ACH support is a genuine advantage over several rivals here. Read recent user reviews alongside the official pages, since support quality and small limits often show up there first.
- ECheck ACH support
- Gateway plus merchant account
- Long history
- Monthly fees apply
- Interface feels older
Helcim
Ideal for: payments with ACH and invoicing
What stands out about Helcim is how well it fits payments with ACH and invoicing. Its strengths include ACH plus cards and invoicing, which cover the core of what most people need from this kind of tool. On the other side, smaller than leaders, so it is not a perfect fit for everyone. Check the pricing page and the free plan terms before you sign up, since plans change and the details matter more than the headline price.
Our view is that Helcim earns its place through ACH plus cards, even though ACH depth varies by plan keeps it from topping the list. It works best for payments with ACH and invoicing, and readers in that group will get the most from it. Before paying, confirm the plan covers the features you need, and check whether the free plan is enough for a first test.
- ACH plus cards
- Invoicing
- Interchange style pricing
- Smaller than leaders
- ACH depth varies by plan
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each option, and we kept only products that exist and work in October 2026 and truly fit the topic. We looked for a clear fit for the stated use, honest pricing, a usable free option or trial where one is claimed, and a track record of regular updates. Where a price or plan could not be confirmed from the vendor, we wrote See website rather than guessing.
We also weighed the drawbacks, not just the strengths. A product with a strong feature set but unclear pricing, weak privacy terms or a limit that blocks common use did not rank as highly as a plainer option that is honest about what it does. Our pick for most people is the option that balances fit, price and ease of use, not the one with the longest feature list.
How to pick an ACH processor
Start with your main use
Write down the one task you will do most often, then check that the product handles it well on its own terms, not through a workaround. If the core task needs a paid plan, that cost is the real starting price, whatever the headline says. A short trial or free plan is the best way to test this, since marketing pages rarely show the limits that appear in daily use.
Check price, limits and exit options
Compare the monthly and yearly prices, the limits on the plan you would actually buy, and what happens to your data if you leave. Look for export options, contract length and support hours before you commit. A cheaper plan that locks your work in, or that charges extra for a feature you need weekly, often costs more over a year than a plainer, clearer plan.
Test before you pay for a year
Use the free plan or trial with real work, not just a quick tour, and note where you get stuck. Check support response times and read recent reviews from people with a similar use case. If two options feel close, pick the one with clearer pricing and simpler terms, since that is the one you are least likely to regret.
Frequently asked questions
What is the best option for best ach processing companies?
For most people, Stripe is a strong starting point because it is best for payments including ACH debits. That said, the right answer depends on your budget and how often you will use it, so try a free plan first and compare two or three options side by side before paying.
Is there a free option for best ach processing companies?
Yes, in most cases. several options offer a free tier or trial offer a free plan or trial, though free plans usually limit features, storage or usage. Check the vendor pricing page for the current limits, since free tiers change, and treat a free plan as a trial for real work rather than a permanent answer.
How do I choose between these options for best ach processing companies?
Start from the task you do most, then filter by price and by the one feature you cannot drop. Shortlist two options, test both with the same real task, and pick the one that felt easier and clearer. Avoid paying for a year up front until that test is done.
Can I switch later if I pick the wrong option for best ach processing companies?
In most cases, yes, but switching costs time. Check export options and contract terms before you start, and keep your own copies of important work where possible. A product with clear export and monthly billing is easier to leave than one with a long contract.
What should I check before paying for best ach processing companies?
Check the full price for the plan you need, the limits on that plan, the privacy terms and the support options. Read recent public reviews, confirm the free plan terms, and make sure the product still works on your device and in your country before you enter payment details.