Best annuity companies in 2026: 8 Compared

- 1
 New York LifeFinancial strengthVisit
- 2
 Northwestern MutualMutual planningVisit
- 3
 MassMutualMutual income annuitiesVisit
- 4
 PrudentialWide annuity rangeVisit
- 5
 Lincoln FinancialRetirement incomeVisit
- New York Life is our pick for buyers who prioritise financial strength and a long mutual company history.
- Northwestern Mutual suits buyers who want a strong mutual insurer with planning support.
- MassMutual is a strong mutual option for income annuities and long-term security.
- Prudential suits buyers who want a large insurer with a wide annuity range.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| New York Life | Financial strength | See website | No | Visit |
| Northwestern Mutual | Mutual planning | See website | No | Visit |
| MassMutual | Mutual income annuities | See website | No | Visit |
| Prudential | Wide annuity range | See website | No | Visit |
| Lincoln Financial | Retirement income | See website | No | Visit |
 Allianz Life | Indexed annuities | See website | No | Visit |
 Nationwide | Annuity choice | See website | No | Visit |
 TIAA | Educators and nonprofits | See website | No | Visit |
The best annuity companies
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews to build this list, focusing on products that fit the topic closely and are still available in October 2026.
New York Life
Ideal for: Financial strength
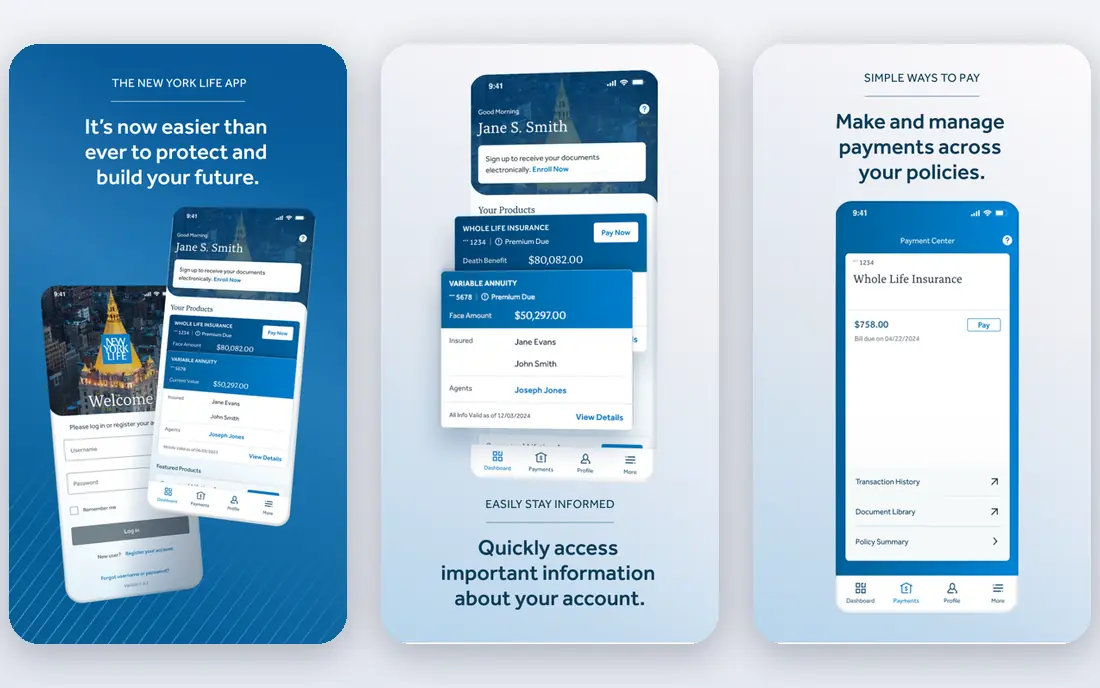
For buyers who want a clear fit, New York Life is aimed at buyers prioritising strength. New York Life is a large mutual insurer known for financial strength. Buyers who prioritise long-term security often shortlist it. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The trade-off is worth naming plainly. Products and pricing need an adviser, and surrender terms apply. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, New York Life is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Strong mutual insurer
- Wide annuity range
- Long history
- Products and pricing need adviser
- Surrender terms apply
Northwestern Mutual
Ideal for: Mutual planning
If that use case sounds familiar, Northwestern Mutual is aimed at buyers wanting planning. Northwestern Mutual is a strong mutual insurer with planning support. Buyers who want advice beside an annuity may value its planning approach. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
On the other side of that strength, Sales are adviser-led, and surrender terms apply. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Northwestern Mutual is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Strong mutual insurer
- Planning support
- Annuity range
- Adviser-led sales
- Surrender terms apply
MassMutual
Ideal for: Mutual income annuities
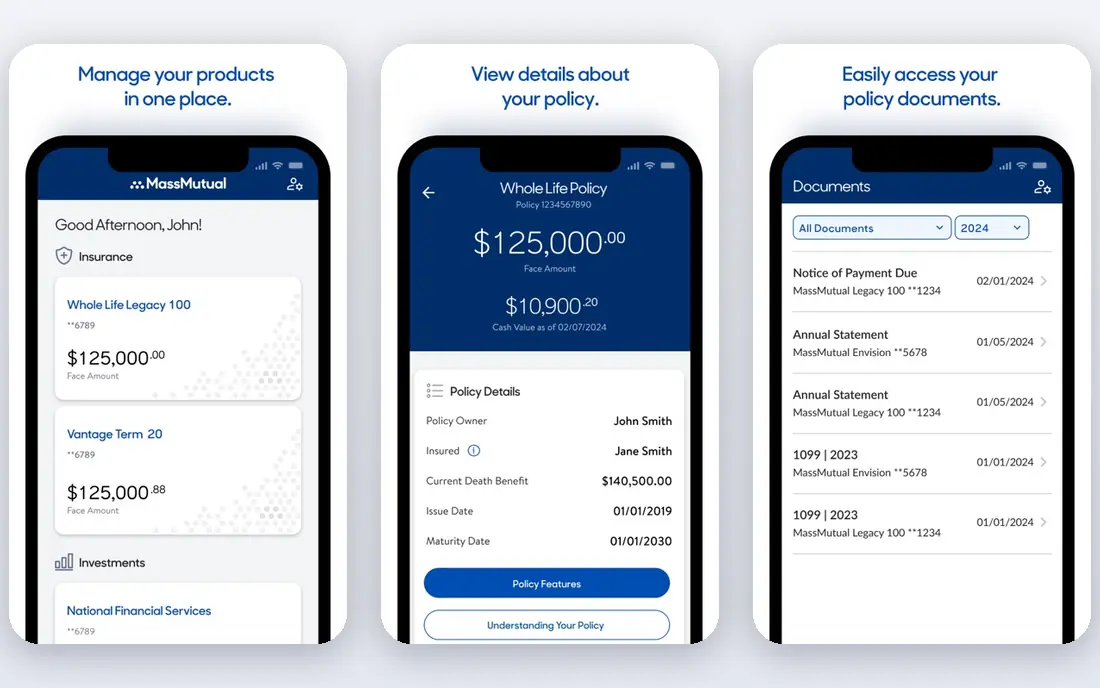
Among the options here, MassMutual is aimed at income-focused buyers. MassMutual is a mutual insurer with a focus on income annuities. Income-focused buyers can explore lifetime income options. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
Before you commit, weigh this part. Sales are adviser-led, and product details vary by state. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, MassMutual is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Mutual insurer
- Income annuity focus
- Strength
- Adviser-led
- Product details vary by state
Prudential
Ideal for: Wide annuity range
For a team or household weighing this choice, Prudential is aimed at buyers wanting choice. Prudential is a large insurer with a wide annuity range and retirement focus. Buyers who want choice across annuity types will find options. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The honest catch comes next. Fees vary by product, and surrender terms apply. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Prudential is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Large insurer
- Wide annuity range
- Retirement focus
- Fees vary by product
- Surrender terms apply
Lincoln Financial
Ideal for: Retirement income
When the main need is the one above, Lincoln Financial is aimed at retirement income buyers. Lincoln Financial focuses on retirement income with an annuity range. Retirement buyers can explore income and protection options. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
Pricing and limits deserve a second look. Fees vary by product, and sales are adviser-led. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Lincoln Financial is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Retirement income focus
- Annuity range
- Planning tools
- Fees vary
- Adviser-led sales
Allianz Life
Ideal for: Indexed annuities
For readers who put this factor first, Allianz Life is aimed at indexed annuity buyers. Allianz Life is known for indexed annuities with income options. Indexed annuity buyers often compare its cap and participation terms. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
A smaller drawback can still matter. Indexed terms are complex, and surrender charges apply. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Allianz Life is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Indexed annuity strength
- Large insurer
- Income options
- Indexed terms are complex
- Surrender charges apply
Nationwide
Ideal for: Annuity choice
In a crowded field, Nationwide is aimed at buyers wanting choice. Nationwide offers a wide annuity range with retirement planning support. Buyers who want choice can compare fixed, variable and indexed options. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
What to check before paying is simple. Fees vary, and product details vary by state. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, Nationwide is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Wide annuity range
- Retirement planning
- Large insurer
- Fees vary
- Product details vary by state
TIAA
Ideal for: Educators and nonprofits
For a first purchase in this category, TIAA is aimed at educators and nonprofit workers. TIAA has a heritage serving educators and nonprofit workers with retirement income. Those workers may find its retirement focus familiar. In practice, that means the product earns its place by doing one job well for that audience, rather than trying to cover every possible use case at once. We compared its official feature page, pricing and public reviews against the other options here, and its best-for label reflects where it looked strongest, not where its marketing claims are loudest.
The limit to keep in mind is this. Eligibility and products vary, and sales are adviser-led. On price, the starting point listed above is not published clearly, so check the vendor site, and the free plan entry is No. If that combination fits your budget and your main use case, TIAA is a sensible shortlist choice. If the catch above is a deal breaker, move to another entry in this list whose strength matches your priority instead.
- Retirement focus
- Educator and nonprofit heritage
- Income options
- Eligibility and products vary
- Adviser-led
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each product, and we kept only products that are still available in October 2026 and that fit the topic closely. Where a vendor did not publish a clear starting price on its own site, we wrote See website rather than guessing. Prices can change, so check the vendor page linked in each product block before you buy.
Choosing an annuity company without locking in a poor deal
Understand the annuity type first: fixed, variable, indexed and immediate annuities work very differently, with different risks and fees. Check surrender periods and charges, since annuities lock money up for years. Check the insurer financial strength ratings from agencies, since your income depends on the insurer paying for decades. Finally, compare fees, income options and inflation protection, and get independent advice, since an annuity is hard to unwind once bought.
Frequently asked questions
What is the best annuity company?
New York Life, Northwestern Mutual and MassMutual are strong mutual choices, while Prudential, Lincoln and Allianz offer wide ranges. The best company depends on annuity type and income needs.
What is an annuity?
An annuity is a contract with an insurer that can provide income, often for retirement. Types include fixed, variable, indexed and immediate annuities, each with different risks.
Are annuities safe?
Income depends on the insurer financial strength, and annuities are long-term contracts with surrender charges. Check insurer ratings and surrender terms before buying.
What are annuity fees?
Fees vary by type, including mortality, administrative, rider and surrender charges. Variable annuities usually have higher fees than fixed annuities.
Should I buy an annuity for retirement?
It depends on income needs, other savings, health and risk tolerance. Get independent financial advice, since annuities suit some retirees and not others.