Best Companies for Infinite Banking in 2026: 8 Options Compared

- 1
 Paradigm LifePeople who want specialist infinite banking guidanceVisit
- 2
 New York LifePeople who want a large, established whole life insurerVisit
- 3
 MassMutualPeople who want a mutual insurer with whole life optionsVisit
- 4
 Guardian LifePeople who want a mutual insurer known for whole lifeVisit
- 5
 Northwestern MutualPeople who want a large insurer with planning supportVisit
- Our pick for most people is Paradigm Life, thanks to its balance of features, ease of use and value for people who want specialist infinite banking guidance.
- New York Life is the strongest alternative when people who want a large, established whole life insurer matters more than a general all-round fit.
- Free and trial options exist, including MassMutual, so you can test the core experience before paying.
- We compared whole life policy options, dividend history approach, loan features, agent and adviser support, and the clarity of costs and risks.
- Check pricing, free plan terms and the exact features you need on the official site before you subscribe, since plans change.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Paradigm Life | People who want specialist infinite banking guidance | See website | See website | Visit |
| New York Life | People who want a large, established whole life insurer | See website | See website | Visit |
| MassMutual | People who want a mutual insurer with whole life options | See website | See website | Visit |
| Guardian Life | People who want a mutual insurer known for whole life | See website | See website | Visit |
| Northwestern Mutual | People who want a large insurer with planning support | See website | See website | Visit |
 Penn Mutual | People who want a mutual insurer with flexible whole life | See website | See website | Visit |
 Lafayette Life | People who want a specialist whole life insurer | See website | See website | Visit |
 OneAmerica | People who want a mutual insurer with whole life and planning | See website | See website | Visit |
The best companies for infinite banking
Infinite banking is a strategy that uses dividend-paying whole life insurance as a personal banking system, borrowing against cash value rather than from a bank. The companies below are insurers and specialist firms associated with this approach, but the strategy needs careful advice and is not suitable for everyone. This is not financial advice; whole life insurance and policy loans carry costs and risks, including reduced death benefits and possible tax consequences if a policy lapses with an outstanding loan. Speak to a licensed financial adviser and a tax professional before buying any policy for infinite banking.
Paradigm Life
Ideal for: People who want specialist infinite banking guidance
Paradigm Life specialises in the infinite banking concept, offering education, policy design help and an agent network for people exploring this strategy. It suits people who want guidance from a firm focused on this approach, rather than a general insurer. Its educational content helps explain how cash value and policy loans are meant to work.
The limits are agent variation and cost, since advice quality depends on the individual agent and whole life policies are high-premium commitments. Any reader considering Paradigm Life should get independent advice as well, and compare its policy recommendations with other insurers.
For readers who want people who want specialist infinite banking guidance, Paradigm Life is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Specialist infinite banking education
- Policy design help
- Agent network
- Advice quality varies by agent
- Policies are high-premium commitments
New York Life
Ideal for: People who want a large, established whole life insurer

New York Life is a large mutual insurer offering whole life policies that are often used in infinite banking designs. It suits people who value insurer size, financial strength and a long track record. Its mutual structure means eligible policyholders may receive dividends, though dividends are not guaranteed.
The trade-offs are agent-led sales and high whole life premiums, which need careful budgeting. For a long-term policy intended for infinite banking, insurer strength and dividend approach matter, and New York Life scores well on both, subject to individual policy terms.
For readers who want people who want a large, established whole life insurer, New York Life is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Large mutual insurer
- Whole life policies
- Long track record
- Policies need an agent
- Premiums are high for whole life
MassMutual
Ideal for: People who want a mutual insurer with whole life options
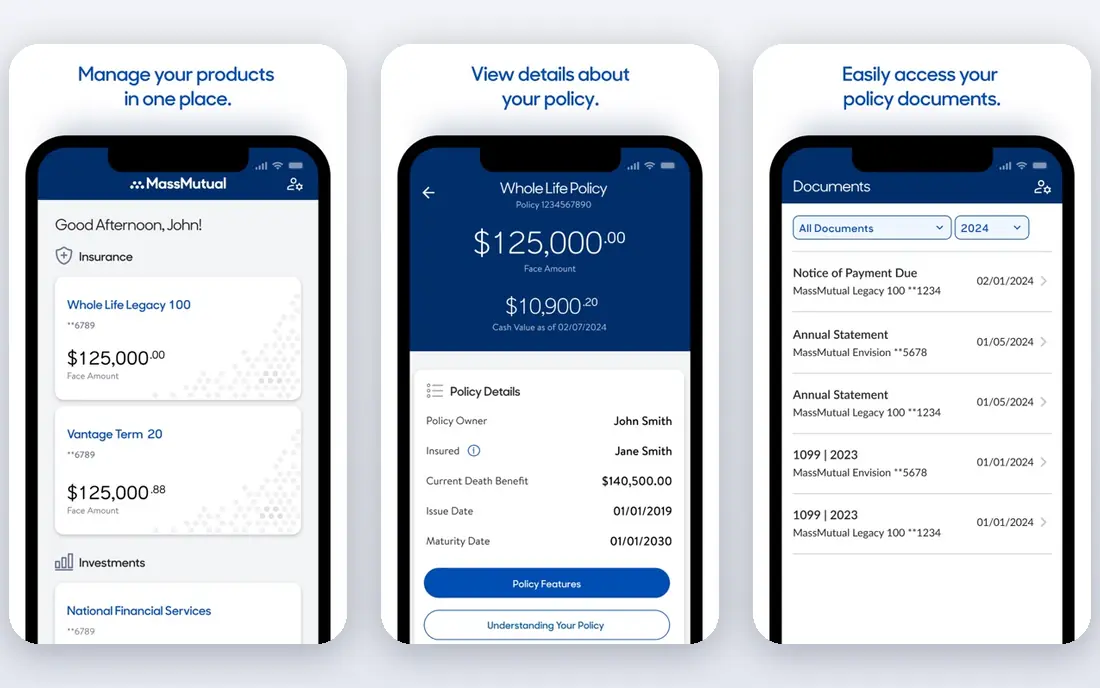
MassMutual is a mutual insurer with whole life policies, loan options and a broad agent network, which makes it a common choice for infinite banking designs. It suits people who want a mutual company where eligible policyholders may share in dividends, though dividends are not guaranteed. Its policy range covers different premium and cash value designs.
The limits are an agent-led process and whole life costs that need careful review. Compare its loan terms, premium flexibility and dividend options with other mutual insurers before committing to a policy.
For readers who want people who want a mutual insurer with whole life options, MassMutual is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Mutual insurer
- Whole life and loan options
- Broad agent network
- Agent-led process
- Whole life costs need careful review
Guardian Life
Ideal for: People who want a mutual insurer known for whole life
Guardian Life is a mutual insurer known for whole life policies, which are frequently used in infinite banking strategies. It suits people who want a well-established mutual company with a focus on whole life design. Its policies can be structured with different premium and loan features, subject to advice.
The trade-offs are agent-led sales and policy complexity, which means independent advice is important. A Guardian policy should be compared on loan interest, cash value growth and premium flexibility, not on brand alone.
For readers who want people who want a mutual insurer known for whole life, Guardian Life is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Mutual insurer
- Whole life policies
- Dividend approach
- Agent-led sales
- Policy complexity needs advice
Northwestern Mutual
Ideal for: People who want a large insurer with planning support
Northwestern Mutual is a large insurer with whole life policies and a financial planning network, which suits people who want insurance as part of a wider financial plan. Its policies are often considered for infinite banking, and its planning support helps integrate a policy with other goals. Its size and track record are reassuring for a long-term commitment.
The limits are agent-led planning and substantial whole life premiums, which need a realistic long-term budget. As with any infinite banking policy, the key is whether the policy design, loan terms and your cash flow actually fit together over decades.
For readers who want people who want a large insurer with planning support, Northwestern Mutual is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Large insurer
- Whole life policies
- Financial planning network
- Agent-led planning
- Whole life premiums are substantial
Penn Mutual
Ideal for: People who want a mutual insurer with flexible whole life
Penn Mutual is a mutual insurer offering whole life policies with flexible premium designs, which suits people exploring infinite banking with a need for some premium flexibility. Its mutual structure and dividend approach are relevant to long-term cash value growth, though dividends are not guaranteed. Its policies are often recommended by infinite banking specialists.
The trade-offs are smaller scale than the largest insurers and an agent-led process. Compare its loan terms and premium flexibility carefully, and get independent advice on whether its policy design fits your cash flow.
For readers who want people who want a mutual insurer with flexible whole life, Penn Mutual is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Mutual insurer
- Whole life options
- Flexible premium designs
- Smaller than the largest insurers
- Agent-led process
Lafayette Life
Ideal for: People who want a specialist whole life insurer
Lafayette Life is a whole life insurer whose policies are used by some infinite banking practitioners. It suits people who want a specialist whole life focus rather than a general insurer with many product lines. Its policy designs can be tailored for cash value growth, subject to advice and underwriting.
The limits are brand scale and agent availability, since it is smaller than the largest mutual insurers. For infinite banking, its relevance depends on the specific policy design an agent proposes, so compare it directly with larger mutual insurers on loan and dividend terms.
For readers who want people who want a specialist whole life insurer, Lafayette Life is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Whole life focus
- Policies used by infinite banking practitioners
- Smaller brand
- Availability depends on agent network
OneAmerica
Ideal for: People who want a mutual insurer with whole life and planning
OneAmerica is a mutual insurer offering whole life policies and planning support, which suits people who want a mutual company for an infinite banking design. Its policies can be structured for cash value and loan access, and its planning network helps integrate insurance with wider financial goals. Its mutual status is relevant to dividend considerations, though dividends are not guaranteed.
The trade-off is an agent-led process and the need for careful policy comparison. As with every option here, the policy design, loan terms and long-term affordability matter more than the insurer name alone.
For readers who want people who want a mutual insurer with whole life and planning, OneAmerica is a sensible shortlist pick, provided the limits above feel acceptable. Compare its pricing page and trial terms before you commit, and check that it covers the exact workflow you need on day one.
- Mutual insurer
- Whole life policies
- Planning support
- Agent-led process
- Policy terms need careful comparison
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each option, and we focused on products that exist and work in October 2026 and truly fit the topic. We looked for a mix of well-known leaders and strong smaller options, rather than a list of near-identical tools. We compared whole life policy options, dividend history approach, loan features, agent and adviser support, and the clarity of costs and risks. We did not claim hands-on testing that did not happen, and where a price or free tier could not be verified from the vendor site, we wrote See website rather than guessing a number.
Choosing the right option for you
Start by understanding the strategy properly, including how whole life premiums, cash value growth, dividends and policy loans actually work. Infinite banking is a long-term, high-premium commitment, not a quick way to access cash, and early years often show low cash value relative to premiums paid.
Work with an adviser who is licensed and who explains fees, surrender charges, loan interest and the risk that unpaid loans reduce the death benefit. Be wary of anyone who presents infinite banking as risk-free, guaranteed, or suitable for everyone, because it is none of those things.
Compare policies from several insurers, including premium flexibility, loan terms, dividend options and the financial strength of the insurer. A policy that looks cheap on premium may be expensive on loan terms or less flexible when you need access to cash.
Before you decide, make a short list of three must-have features and one deal-breaker, then test only the two or three options that meet that list. A focused trial will tell you more than a week of comparing feature tables, and it keeps the decision tied to your real work rather than to marketing claims.
Frequently asked questions
What are the best best companies for infinite banking?
The best choice depends on your needs, but Paradigm Life suits most people, while New York Life is stronger for people who want a large, established whole life insurer. Start with your must-have features, then trial the top two options before paying.
Is there a free option for best companies for infinite banking?
Yes, several options here offer a free plan or a free trial, including MassMutual. Free plans usually limit advanced features, so check which tools you actually need before judging a free tier.
How much do best companies for infinite banking cost?
Costs vary widely, and many vendors use quote-based pricing, so the pricing page is the reliable source. Where we could not verify a current price, we wrote See website rather than guessing, and you should get a written quote for team plans.
Which option is best for beginners?
Paradigm Life is the easiest starting point for most beginners, thanks to its clear setup and guidance. If you want the simplest possible tool, look at the free or trial options first and choose the one whose interface feels clearest to you.
How should I choose between these options?
List your top three needs, check integrations and pricing for those needs, and run a short trial with real work. The option that handles your daily tasks smoothly, with support you can reach, is usually the right pick, even if a rival has a longer feature list.