Best Credit Builder Apps in 2026: 7 Apps Compared

- 1
 SelfSavings plus credit buildingVisit
- 2
 Chime Credit BuilderBanking plus credit buildingVisit
- 3
 MoneyLion Credit Builder PlusAll-in-one money appVisit
- 4
 KikoffLow monthly costVisit
- 5
 Experian BoostFree bill reportingVisit
- Self suits savers who want a credit builder account plus a secured card in one place.
- Kikoff suits people who want a low monthly cost and reporting to all three bureaus.
- Experian Boost suits people who already pay bills and want a free way to add payment history.
- Chime and Current suit people who want banking plus credit building in a single app.
- This is general information, not financial advice; credit builder results vary with payment history, debts, and the bureaus that receive your reports.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Self | Savings plus credit building | See website | No | Visit |
| Chime Credit Builder | Banking plus credit building | See website | No | Visit |
| MoneyLion Credit Builder Plus | All-in-one money app | See website | No | Visit |
| Kikoff | Low monthly cost | $5/month | No | Visit |
| Experian Boost | Free bill reporting | See website | Yes | Visit |
 Current Build | Banking with cash back | See website | No | Visit |
 Step | Young builders and families | See website | Yes | Visit |
The best credit builder apps
A thin credit file makes it hard to get approved for cards, loans, or rentals, and credit builder apps exist to fix that problem. They report your payments to one or more credit bureaus, which builds payment history, the largest single factor in most credit scores. We compared official product pages, pricing, and public reviews for the apps below, looking at which bureaus they report to, monthly cost, whether a bank account or deposit is required, and what extras you get.
Costs and terms change, so we list See website where we did not verify a current price on the vendor's own page. Check fees, reporting bureaus, and cancellation terms before signing up, and remember that on-time payments matter more than any app choice.
Self
Ideal for: Savings plus credit building
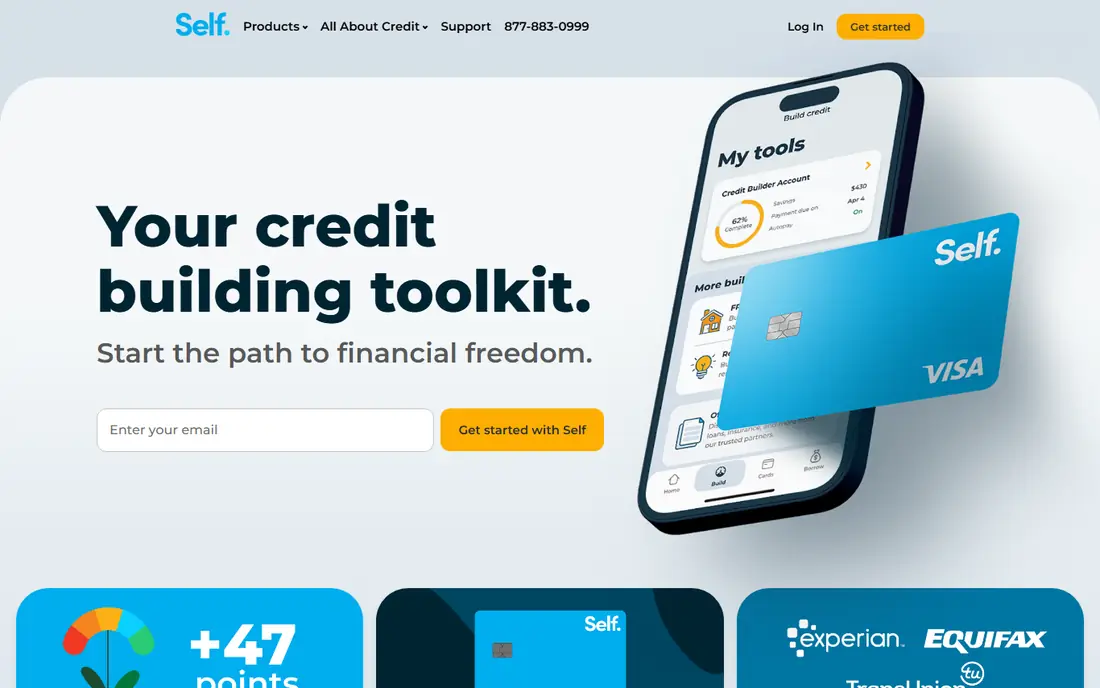
Self offers a credit builder account that works like a small savings plan reported to the bureaus, plus a secured credit card for everyday spending. Payments on the builder account go to a certificate of deposit style account that you receive at the end of the term, so you build savings and payment history at once. Rent reporting is also available for people who want credit for rent they already pay.
The trade-off is cost. Builder accounts charge a monthly fee, and the secured card requires a deposit, so read the plan terms closely. Self suits people who want a structured savings habit alongside credit building and can commit to regular payments.
- Credit builder account plus secured card option
- Rent reporting available
- Savings grow as you pay
- Monthly fees apply to builder accounts
- Results depend on consistent payments
Chime Credit Builder
Ideal for: Banking plus credit building
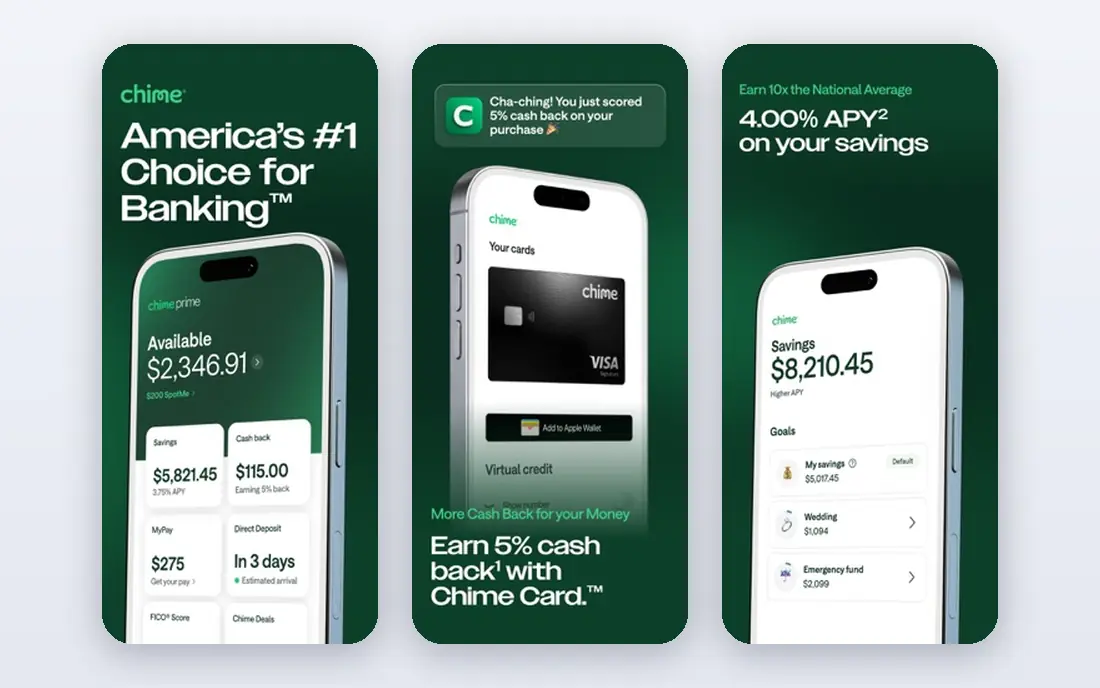
Chime Credit Builder is a secured Visa card tied to a Chime checking account. You move money from checking to the card, spend within that amount, and Chime reports your payments to all three major bureaus. There is no annual fee and no interest, since you spend only money you already moved to the card.
The catch is the setup. You need a Chime checking account and a qualifying direct deposit to open the card, so it suits people already banking with Chime or willing to switch. If you want a card that grows into an unsecured card, other options may fit better.
- No annual fee or interest on the secured card
- Works with Chime checking
- Reports to all three bureaus
- Requires a Chime account and qualifying direct deposit
- No traditional credit limit increase path
MoneyLion Credit Builder Plus
Ideal for: All-in-one money app
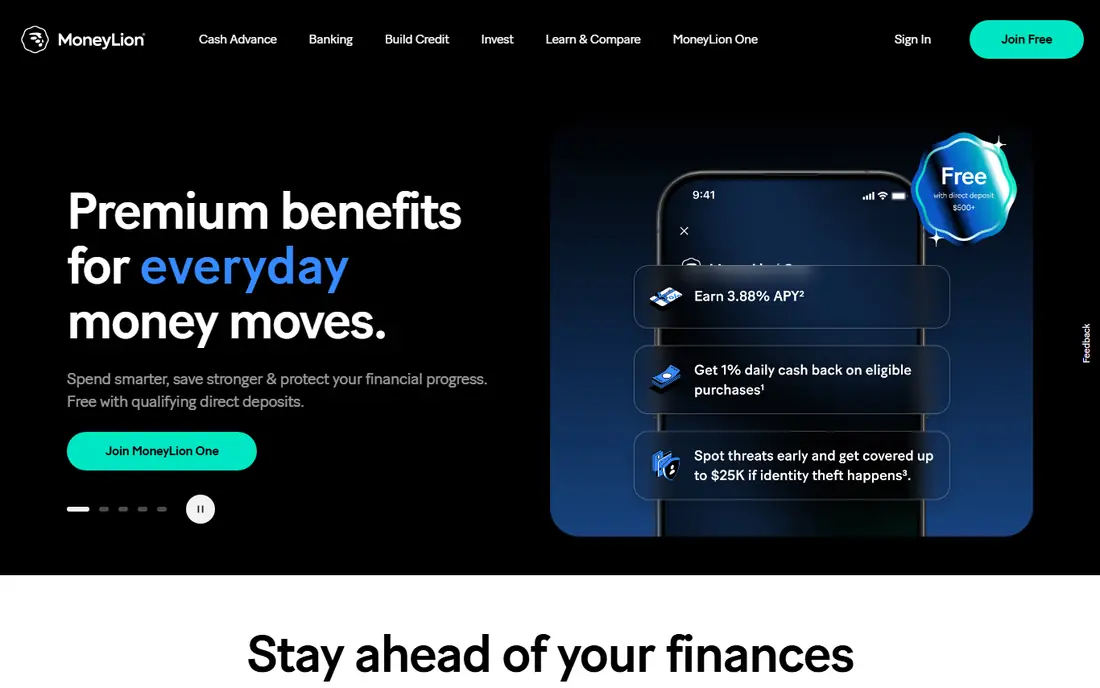
MoneyLion's Credit Builder Plus sits inside a broad money app that also offers banking, investing, cash advances, and credit monitoring. The builder membership reports to the bureaus and pairs with a secured card option in some plans, so your everyday money and credit building live in one app. Credit monitoring alerts help you watch changes as you build.
The bundle is both the appeal and the drawback. If you only want credit building, the wider membership may feel like more than you need, and pricing tiers take care to compare. MoneyLion suits people who want one app for several money tasks and will use the extras.
- Combines banking, investing, and credit building
- Credit monitoring included
- App covers many money needs
- Membership pricing can confuse
- Credit builder is one part of a larger bundle
Kikoff
Ideal for: Low monthly cost
Kikoff sells a simple credit account with plans starting at $5 per month, reported to Equifax, Experian, and TransUnion. You pay monthly and build payment history, utilization, and account age, and higher tiers add larger tradelines, tri-bureau reports and scores, and bill reporting. Rent reporting is available as an add-on for rent you already pay.
Kikoff does not give you a card to spend with on the basic plan, so it suits people who want a low-cost, set-and-forget builder rather than a spending tool. Check the tier you choose, since features and tradeline size differ across the $5, $20, and $35 plans shown on its site.
- Plans start at $5 per month
- Reports to all three bureaus
- No credit check to sign up
- Rent and bill reporting add-ons
- No card for everyday spending on the basic plan
- Higher tiers cost more per month
Experian Boost
Ideal for: Free bill reporting
Experian Boost is the free option on this list, and it works differently from the rest. Instead of a new account, it connects to your bank account and adds eligible phone, utility, streaming, and rent payments to your Experian credit file. Many users see a score change right away, since the payments already exist.
The limit is scope. Boost affects only your Experian file, so lenders that check Equifax or TransUnion will not see the added history. It pairs well with a builder account that reports to all three bureaus, and it costs nothing to try if you already pay eligible bills.
- Free to use
- Adds bill and rent payments to your Experian file
- Instant results for many users
- Only affects your Experian file, not Equifax or TransUnion
- Only eligible bills count
Current Build
Ideal for: Banking with cash back
Current Build lets you build credit through a secured card inside the Current banking app, with cash back on eligible purchases and savings pods for goals. Payments report to the bureaus, and the app also offers early direct deposit, fee-free overdraft features, and savings tools, so credit building is part of everyday banking.
Current suits people who want banking and credit building together and will use the app as their main account. If you prefer to keep your bank separate from your credit builder, a standalone option such as Kikoff or Self may fit better.
- Credit building inside a full banking app
- Cash back on eligible purchases
- Savings tools included
- Credit building requires a Current account
- Terms tied to account activity
Step
Ideal for: Young builders and families
Step is an all-in-one money app built for younger users and families, with a Visa card that builds credit with every purchase and savings rewards on its paid tier. The free account covers basic banking, while Step Black adds cash back and a higher savings reward. Parents can give teens their own cards with controls and alerts, which makes Step a natural pick for families teaching money habits.
Credit building features and rewards differ by tier, so check which plan covers the card reporting you want. Step suits younger builders and families who want banking, saving, and credit building in one app with a simple design.
- Free basic account
- Step Visa Card builds credit with purchases
- Family-friendly design
- Savings rewards on paid tiers
- Credit building features differ by plan
- Some rewards need a paid Step Black tier
How we picked these
We compared official product pages, pricing, and public reviews, checking which bureaus each app reports to, monthly cost, whether a bank account or deposit is required, and what extras are included. We favored apps that are active in October 2026, report to at least one major bureau, and publish clear pricing and terms. Where we could not verify a current price on the vendor's own page, we list See website rather than guessing.
How to choose a credit builder app
Start with the bureaus. An app that reports to all three bureaus gives lenders the fullest picture, while a single-bureau option such as Experian Boost helps only that file. Next, compare total monthly cost against what you get, and favor the lowest cost option that reports to the bureaus you need. Avoid paying for extras you will not use.
Then check the fine print. Look for fees, deposit requirements, cancellation terms, and whether the account reports as revolving or installment credit, since that affects your credit mix. Finally, protect the habit itself: set up automatic payments so every payment lands on time, since a single missed payment can undo months of progress.
Frequently asked questions
Do credit builder apps really raise my score?
They can, but nothing is guaranteed. On-time payments build payment history, which helps most scores over time, while missed payments, high debts, and short credit history can hold scores back. Results vary by person and by which bureaus receive your reports.
How long does credit building take?
Most people need several months of on-time payments before seeing a clear change, and larger gains usually take a year or more. Keep payments on time, keep other debts low, and avoid opening many new accounts at once while you build.
Is a credit builder app better than a secured credit card?
Both can work, and they serve different needs. A secured card gives you a spending tool and reports revolving credit, while a builder account reports installment-style payments and often builds savings. Some people use both, since a mix of account types can help a credit file.
Do I need a bank account to use a credit builder app?
It depends on the app. Chime Credit Builder and Current Build need their own accounts, while Kikoff and Self work with an external bank account for payments. Check the requirements before signing up so you are not surprised.
Can I cancel a credit builder account?
Most apps let you cancel, but terms differ. Some return your savings or deposit at the end of a term, while others close the account and stop reporting. Read the cancellation terms and check whether closing the account changes your credit file before you cancel.