Best Credit Building Apps in 2026: 7 Apps Compared

- 1
 KikoffLow-cost credit buildingVisit
- 2
 SelfCredit builder and savingsVisit
- 3
 Chime Credit BuilderBanking with credit buildingVisit
- 4
 Current Build CardBanking with credit buildingVisit
- 5
 Experian BoostFree reports and bill reportingVisit
- Kikoff suits low-cost credit building, with plans from 5 USD per month reporting to all three bureaus.
- Self suits savers who want a credit builder account, a secured card and rent reporting in one toolkit.
- Chime and Current suit bank account users who want credit building built into everyday banking.
- Experian Boost suits people who want free credit reports and a way to get bills counted toward scores.
- MoneyLion suits users who want credit building plus banking, investing and cash advances in one app.
- StellarFi suits card users who want a smart card that grows spending power with responsible use.
- No app can guarantee a score increase, and results depend on on-time payments, balances and your full credit file.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Kikoff | Low-cost credit building | $5/month | No | Visit |
| Self | Credit builder and savings | See website | No | Visit |
| Chime Credit Builder | Banking with credit building | Free | Yes | Visit |
| Current Build Card | Banking with credit building | See website | Yes | Visit |
| Experian Boost | Free reports and bill reporting | Free | Yes | Visit |
 MoneyLion | All-in-one money app | See website | Yes | Visit |
 StellarFi | Smart credit card | See website | No | Visit |
The best credit building apps
Credit building apps work by creating a payment history that gets reported to credit bureaus. Some use a small credit line, some use a savings-backed account, and some report bills you already pay. The apps below all report to bureaus or help you build credit through banking, and we checked each official homepage before listing it.
A short disclaimer: this article is general information, not financial advice. Credit results vary, fees and terms change, and no app can promise a specific score gain. Read the terms for any app before signing up, and check whether it reports to all three bureaus, since that affects how widely your history counts.
Kikoff
Ideal for: Low-cost credit building
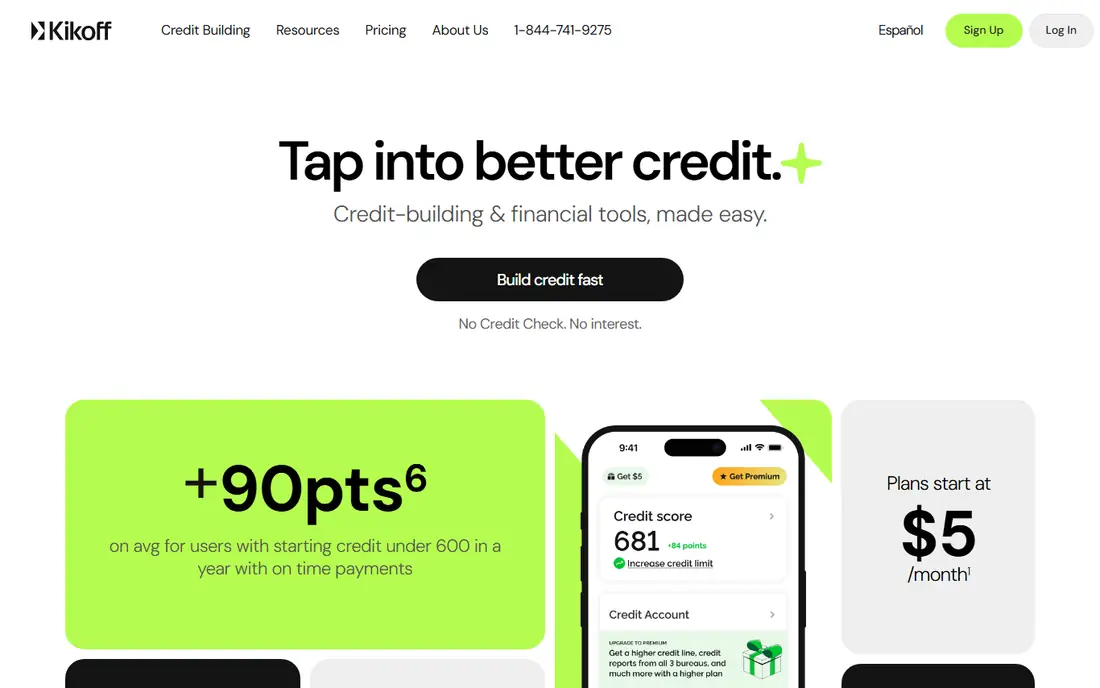
Kikoff offers credit building and financial tools, with plans starting at 5 USD per month and no credit check or hidden fees or interest stated on its homepage. Its Basic plan reports a 750 USD tradeline to all three bureaus, with a weekly credit report, rent reporting to Equifax and TransUnion, and tools and tracking. Premium costs 20 USD per month with a 2,500 USD tradeline and tri-bureau reports, while Ultimate costs 35 USD per month with a 3,500 USD tradeline, identity theft insurance and privacy protection.
Kikoff suits people who want a simple, low-cost tradeline with no credit check. The Basic plan is cheap enough to keep for a year, which helps account age, one of the factors Kikoff highlights alongside payment history and utilization. The trade-off is that there is no free tier, so compare the monthly cost against a free banking-based builder before paying.
- Plans from 5 USD per month
- Reports to Equifax, Experian and TransUnion
- 45-day money-back guarantee
- Rent and bill reporting options
- No free plan
- Higher tiers cost 20 USD or 35 USD per month
- Bank fees may apply when accounts are debited
Self
Ideal for: Credit builder and savings
Self describes itself as a credit building toolkit, with a credit builder account, a secured credit card with no credit check and high approval rates, and rent reporting to all three bureaus. Its homepage states an average lift of 47 points for credit builder account users. The combination of an account that builds savings while you pay, plus a card for spending power, covers two credit factors at once: payment history and account mix.
Self suits people who want to save and build credit together. The credit builder account locks payments into savings you receive at the end, which teaches a savings habit while building history. The secured card adds revolving credit, which helps utilization when balances stay low. Check current plan pricing on the site, since Self offers several account sizes and terms.
- Credit builder account plus secured card
- Rent reporting to all three bureaus
- Average lift of 47 points stated on its homepage for credit builder accounts
- Pricing varies by plan and needs checking on the site
- Secured card needs a savings-backed balance
Chime Credit Builder
Ideal for: Banking with credit building
Chime offers fee-free banking with checking, savings, credit and cash back, through partner banks The Bancorp Bank, N.A. and Stride Bank, N.A., members FDIC. Its homepage notes no credit check to open an account, no opening deposit required, access to more than 47,000 fee-free ATMs, and a Prime membership with 5 percent cash back and 4.00 percent APY on savings with qualifying direct deposits. Credit building is part of its banking offer, with growth of up to 70 points mentioned for Prime members.
Chime suits people who want one app for banking and credit building without a separate monthly fee. Since there is no credit check to open an account, it is accessible to people rebuilding credit. The limit is that the best credit features tie to qualifying direct deposits and membership, so read the current terms to see what your account qualifies for.
- Fee-free banking through partner banks
- No credit check to open an account
- Deposits insured up to 250,000 USD through partner banks
- Credit builder features need a Chime account and qualifying deposits
- Chime is a financial technology company, not a bank itself
Current Build Card
Ideal for: Banking with credit building
Current is a banking app with paycheck advances up to 1,000 USD, fee-free overdraft, payday up to 2 days early, savings up to 4.00 percent, and a credit building section. Its homepage states that credit building can raise a score by over 80 points after six months, plus 1 percent cash back on eligible purchases, and notes more than 6 million members. Support is available 24/7, with cash deposits at stores such as CVS and Walgreens.
Current suits people who already use a banking app and want credit building without a separate subscription. The Build Card approach lets everyday spending build history, which is easier to sustain than a separate monthly payment. As with any builder, the stated gain is an average-style claim, not a promise for every user, so judge it on whether the banking features fit you too.
- Credit building section with a stated gain of over 80 points after six months
- 1 percent cash back on eligible purchases
- More than 40,000 fee-free ATMs
- Credit building gains depend on use and your full credit file
- Some features need a Current account and direct deposit
Experian Boost
Ideal for: Free reports and bill reporting
Experian offers a free credit report and FICO score, with a Boost feature that raises scores by counting bills such as cell phone, utilities, streaming services and eligible rent payments. Its homepage also notes cash advances from 25 USD to 250 USD with no interest or late fees, card matches that will not ding scores if you are not approved, and a free app with credit alerts, insights and financial tools.
Experian Boost suits people who want a free starting point, especially renters and bill payers with thin credit files. If you already pay utilities and streaming on time, Boost turns those payments into credit history at no cost. The limit is scope: Boost works with Experian data, so it may not move scores from other bureaus in the same way. Still, free is hard to argue with as a first step.
- Free credit report and FICO score
- Boost counts bills such as phone, utilities, streaming and eligible rent
- Free app with alerts and tools
- Boost affects Experian scores, not all bureau scores equally
- Bill reporting only helps if you pay those bills on time
MoneyLion
Ideal for: All-in-one money app
MoneyLion offers borrowing, earning and learning about money, with Credit Builder Plus to help improve scores, Instacash advances up to 500 USD, personal loans up to 100,000 USD, managed investing and free credit monitoring alerts. Its homepage notes more than 18 million customers and 1,200 partners, with a 4.7 app rating shown. MoneyLion One membership adds premium benefits with qualifying direct deposits.
MoneyLion suits people who want credit building inside a wider money app, rather than a single-purpose builder. If you also want investing, cash advances and spending tools, the all-in-one approach saves juggling apps. The trade-off is complexity: a focused builder such as Kikoff is simpler if credit is your only goal. Compare MoneyLion's Credit Builder Plus terms against a standalone plan before choosing.
- Credit Builder Plus for building credit
- Banking, investing, cash advances and credit monitoring in one app
- Free credit monitoring alerts
- Many features in one app can feel busy
- Some premium benefits need qualifying direct deposits
StellarFi
Ideal for: Smart credit card
StellarFi offers a smart credit card for every credit score, with levels from Silver (secured, up to 500 USD limit, 100 percent deposit) through Gold (semi-secured, up to 5,000 USD limit, 25 to 75 percent deposit) to Stellarite (unsecured, up to 25,000 USD limit, no deposit). Its homepage notes that all credit scores are welcome, that you can qualify based on income and bank account, and that better habits open higher spending power and rewards over time. Tools include a credit dashboard, a smart action plan and offers picked for your credit history.
StellarFi suits people who want a real credit card path, not just a tradeline. Starting secured and working up to unsecured with one card avoids applying for new cards at each stage, which can help account age. The fees matter: Gold costs 49 USD per year and Stellarite 99 USD per year, and the card is digital only for now, so check that it works where you shop.
- Card levels from secured Silver to unsecured Stellarite
- All credit scores welcome
- Credit dashboard and action plan tools
- Gold has a 49 USD annual fee and Stellarite a 99 USD annual fee
- Digital card only, with no physical card yet
How we picked these
We compared official homepages, pricing and reporting, favoring apps that report to at least one major bureau, state their fees clearly and are actively maintained. We covered low-cost tradelines, savings-backed accounts, banking builders, free bill reporting and a smart card, because different credit situations need different tools. One well-known credit app was dropped because its homepage domain is now listed for sale, and we only list apps whose official sites we verified.
How to build credit safely with an app
Start with one tool, not three at once. A single on-time payment history over 6 to 12 months helps more than several new accounts opened together, which can lower your average account age. Pick the tool that fits your budget: a free option such as Experian Boost or a banking builder if money is tight, or a low-cost plan such as Kikoff Basic if you want a dedicated tradeline.
Next, pay on time, every time, and keep balances low. Payment history and utilization are the two factors these apps target, and a missed payment can undo months of progress. Set autopay where possible, keep card use well below the limit, and check your reports regularly for errors. If you spot an error, dispute it with the bureau directly rather than paying a service to do it.
Finally, review costs yearly. A 5 USD monthly plan costs 60 USD a year, and a 35 USD plan costs 420 USD, so ask whether the extra tradeline size and features justify the price. Once your score and history improve, you may qualify for a regular credit card with no fee, at which point a paid builder may no longer be worth it. Build credit as a step toward better terms, not as a permanent subscription.
Frequently asked questions
What is the best credit building app?
Kikoff is the best low-cost choice at 5 USD per month, while Self suits savers who want an account plus a card. Chime and Current suit banking users who want building built in, and Experian Boost is the best free starting point. Pick based on budget and whether you want a standalone builder or a banking app.
How long does it take to build credit with an app?
Most users see movement in 3 to 6 months with on-time payments, and stronger results after 12 months as account age grows. Results vary with your starting file, balances and other accounts. No app can promise a specific gain or timeline.
Do credit building apps report to all three bureaus?
Some do and some do not. Kikoff and Self report to Equifax, Experian and TransUnion, while other tools may report to one or two bureaus, or only affect one bureau's score. Check the reporting details on the app's site before signing up, since wider reporting helps more lenders see your history.
Can I build credit without a credit card?
Yes. Credit builder accounts, tradeline plans such as Kikoff, rent reporting and bill reporting through Experian Boost all build history without a traditional credit card. A secured card is another route if you want revolving credit, but it is not required to start.
Do credit building apps charge fees?
Some are free, such as Experian Boost and banking-based builders, while others charge monthly fees from 5 USD upward or annual card fees. Always read the fee schedule, including late fees, interest and any bank fees on debits, before signing up.
Will a credit building app hurt my credit score?
A new account can cause a small, short-term dip from the inquiry or lower average account age, but on-time payments usually help over time. Missed payments, high balances and unpaid fees can hurt, so only sign up for a plan you can pay reliably each month.