Best Credit Monitoring Services in 2026: 9 Compared

- 1
 Credit KarmaFree two-bureau monitoring for most peopleVisit
- 2
 ExperianFree FICO Score 8 and Experian reportVisit
- 3
 TransUnionFree daily TransUnion scores and alertsVisit
- 4
 EquifaxPaid three-bureau monitoring and ID protectionVisit
- 5
 Capital One CreditWiseFree FICO Score 8 with dark web alertsVisit
- You can get free credit monitoring from Credit Karma, Capital One CreditWise, TransUnion, Experian and Credit Sesame, so paying is only worth it for extra bureaus, FICO scores or identity protection.
- Credit Karma is our pick for most people: it watches both TransUnion and Equifax and gives free VantageScore 3.0 scores from each.
- Paid plans we could verify range from $9.95 per month (Equifax Complete) to $19.95 to $39.95 per month (myFICO) and $15 per month for Aura Individual.
- Monitoring only alerts you to problems. A credit freeze, which the FTC says is free, is what blocks new accounts.
- This article is general information, not financial advice. Check each company's terms and your own credit reports.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Credit Karma | Free two-bureau monitoring for most people | Free | Yes | Visit |
| Experian | Free FICO Score 8 and Experian report | Free | Yes | Visit |
| TransUnion | Free daily TransUnion scores and alerts | Free | Yes | Visit |
| Equifax | Paid three-bureau monitoring and ID protection | $9.95 per month (Complete) | Yes | Visit |
| Capital One CreditWise | Free FICO Score 8 with dark web alerts | Free | Yes | Visit |
 myFICO | FICO scores from all three bureaus | $19.95 per month | Yes | Visit |
 Aura | Credit monitoring bundled with identity protection | $15 per month | Free trial (14 days) | Visit |
 NerdWallet | Free monitoring inside a budgeting app | Free | Yes | Visit |
 Credit Sesame | Free monitoring with optional paid upgrades | See website | Yes | Visit |
The best credit monitoring services
Credit monitoring watches your credit report and alerts you when something changes, such as a new account or a hard inquiry. The nine services below include free tools, bureau-owned apps and paid plans, and we say clearly where the free tier ends.
Credit Karma
Ideal for: Free two-bureau monitoring for most people
Credit Karma is the easiest place to start because the monitoring is free and covers two of the three major bureaus. Its monitoring page says it watches your TransUnion and Equifax reports, sends push and email alerts for changes such as a new hard inquiry or a new credit card, and gives free VantageScore 3.0 scores and reports from both bureaus.
It also notifies you if your personal information shows up in a public data breach, and shows your credit lock status at TransUnion and Equifax. The page is honest about limits: monitoring only covers credit report activity, so it will not catch a fraudulent bank withdrawal or a tax refund filed with your Social Security number.
Credit Karma is also a marketplace for credit cards and loans, so expect offers. The App Store listing mentions a Credit Karma Plus subscription rolling out gradually, with identity protection features, but we could not confirm its price.
- Monitors TransUnion and Equifax reports
- Free VantageScore 3.0 scores from both bureaus
- Alerts for new inquiries and new accounts
- Does not monitor Experian
- Does not catch bank fraud or tax refund fraud
Experian
Ideal for: Free FICO Score 8 and Experian report
Experian is one of the three bureaus, and its app is the way to monitor your Experian file directly. The App Store listing says a free membership includes your Experian credit report and FICO Score, plus credit monitoring that tells you if accounts are opened in your name or new inquiries appear on the report.
Experian Boost, also free, lets you add payments such as phone, utilities, streaming services and eligible rent payments to your Experian file. The listing says results vary and not every lender uses Boost-affected scores.
Paid membership adds CreditLock, bill negotiation and Experian Cash advances of $25 to $250. We could not find a monthly price on the pages we could open, so check the site. The iOS app has a 4.8 rating from more than 2.7 million ratings.
- Free membership with no credit card needed
- FICO Score 8 and Experian credit report
- Experian Boost can add on-time bills to your file
- Free monitoring covers Experian only
- Paid membership price not stated on pages we checked
TransUnion
Ideal for: Free daily TransUnion scores and alerts
TransUnion's official app gives free credit scores, free credit reports and free credit monitoring with no credit card needed. The listing says scores use the VantageScore 3.0 model, that your TransUnion report and score can refresh daily, and that you get an alert for a critical change.
The business model is stated plainly: offers are provided by Bankrate, which pays TransUnion Interactive when you interact with them, and that revenue affects how offers are ordered. Treat the offers as ads.
Upgrading adds quarterly three-bureau reports and identity monitoring, but the price was not listed on the pages we could read. The app requires you to be 18 or older and has a 4.6 rating from about 39,000 ratings.
- Free scores, reports and credit monitoring
- Daily refreshes and alerts on critical changes
- No credit card required
- Monitors TransUnion only on the free plan
- Offers come from an advertiser, Bankrate
Equifax
Ideal for: Paid three-bureau monitoring and ID protection
Equifax has a free account and a paid ladder. The myEquifax listing says a free account gives you your Equifax credit report with daily updates and daily one-bureau VantageScore 3.0 updates. Monitoring alerts and identity protection are described as paid upgrades.
The Equifax site lists Equifax Complete at $9.95 per month or $99.95 per year, Complete Premier at $19.95 per month or $199.95 per year, and a Family Plan at $29.95 per month or $299.95 per year. The app listing says Premier includes access to reports and scores from Equifax, TransUnion and Experian, credit monitoring alerts, a dark web scan and support from identity theft specialists.
If you only want alerts, a free service will do. Equifax makes more sense if you want a paid plan with specialists to help you recover from identity theft.
- Free myEquifax account with daily report updates
- Paid plans add monitoring, dark web scans and ID restoration
- Family plan covers a second adult and up to 4 children
- Credit monitoring sits behind paid plans
- Several tiers to compare
Capital One CreditWise
Ideal for: Free FICO Score 8 with dark web alerts
CreditWise is free, and the listing says it is available to every adult 18 or older in the US with a Social Security number and a TransUnion report on file. You do not need to be a Capital One customer, per the description.
You get a TransUnion-based FICO Score 8 with updates as often as daily, access to your TransUnion report, a Credit Simulator and alerts about select changes to TransUnion or Experian reports. It also alerts you if your Social Security number or email appears on the dark web, and when new names or addresses are linked to your Social Security number on a credit application.
Capital One says the score may not match the model your lender uses. The iOS app shows a 4.8 rating from more than 310,000 ratings, which is a strong signal for a free tool.
- Free FICO Score 8 based on TransUnion data
- Alerts for select TransUnion and Experian changes
- Dark web alerts for Social Security number and email
- Score is based on TransUnion data only
- Must have a TransUnion report on file
myFICO
Ideal for: FICO scores from all three bureaus
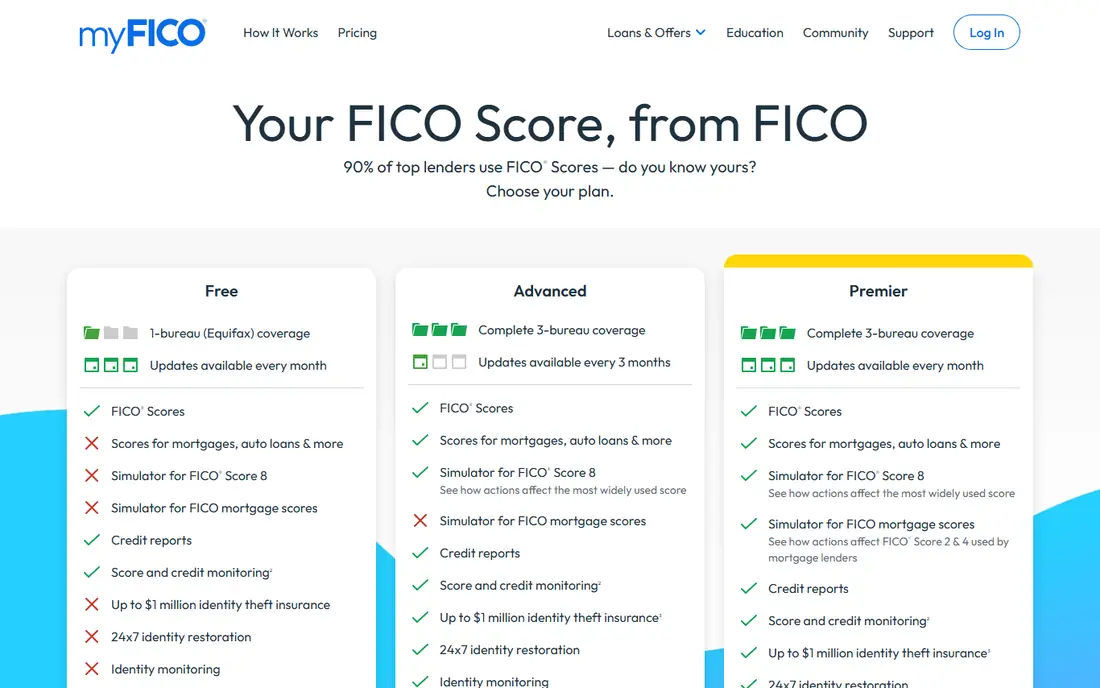
myFICO is run by Fair Isaac, the company behind FICO scores, and it is the choice if you want the score lenders often use. The plans page lists a Free plan with Equifax-only monthly updates, then Basic at $19.95 per month (Experian, monthly updates), Advanced at $29.95 per month (three bureaus, updates every 3 months) and Premier at $39.95 per month (three bureaus, monthly).
All paid plans list identity theft insurance up to $1M and 24x7 identity restoration, and Advanced and Premier add identity monitoring. Premier adds a mortgage simulator. The page also says subscriptions renew automatically and that Basic and Advanced do not allow cancellation refunds.
These plans cost far more than the free tools, so pay only if you need FICO versions for a mortgage, auto loan or card application. The App Store listing shows a 4.8 rating from about 52,000 ratings.
- Official FICO scores, including versions used in mortgage and auto lending
- Three-bureau plans
- Identity theft insurance up to $1M on paid plans
- Most expensive plans in this list
- Basic and Advanced allow no cancellation refunds
Aura
Ideal for: Credit monitoring bundled with identity protection
Aura is an identity protection service where credit monitoring is one part of the package. Its pricing page lists an Individual plan for one adult and 10 devices at $15 per month, or $12 per month billed annually, with three-bureau credit monitoring and a 14-day free trial. Couple is $29 monthly ($22 annually) and Family is $50 monthly ($32 annually) for five adults.
The site says Aura's Credit Monitoring with Credit Lock tracks Experian, TransUnion and Equifax and includes Experian Credit Lock. Eligible annual plans bought through Aura's websites or customer support have a 60-day refund. Full access depends on identity verification and credit eligibility.
It makes sense if you want one bill for credit, identity and device protection. If you only want alerts, free options cover most of the job.
- Three-bureau credit monitoring on all adult plans
- Includes Experian Credit Lock
- 60-day refund on eligible annual plans
- Costs more than free monitoring
- Free trial can be redeemed once per customer
NerdWallet
Ideal for: Free monitoring inside a budgeting app
The free NerdWallet app combines budgeting with credit monitoring. The App Store listing describes 24/7 credit monitoring, alerts for important changes, and explanations of what affects your score, along with transaction tracking and savings suggestions.
It is a good fit for people who want to see credit and spending in one place. The listing does not say which credit bureau or score model it uses, and we could not open the site's credit page, so check the app before relying on it.
NerdWallet also promotes financial products. The listing discloses a paid promotion for a cash account offered by a brokerage partner, so treat promotions as marketing.
- Free app with 24/7 credit monitoring, per its listing
- Budgeting and spending tools in the same app
- Rating of 4.8 from over 125,000 App Store ratings
- We could not confirm which bureau it monitors
- Promotes financial products
Credit Sesame
Ideal for: Free monitoring with optional paid upgrades
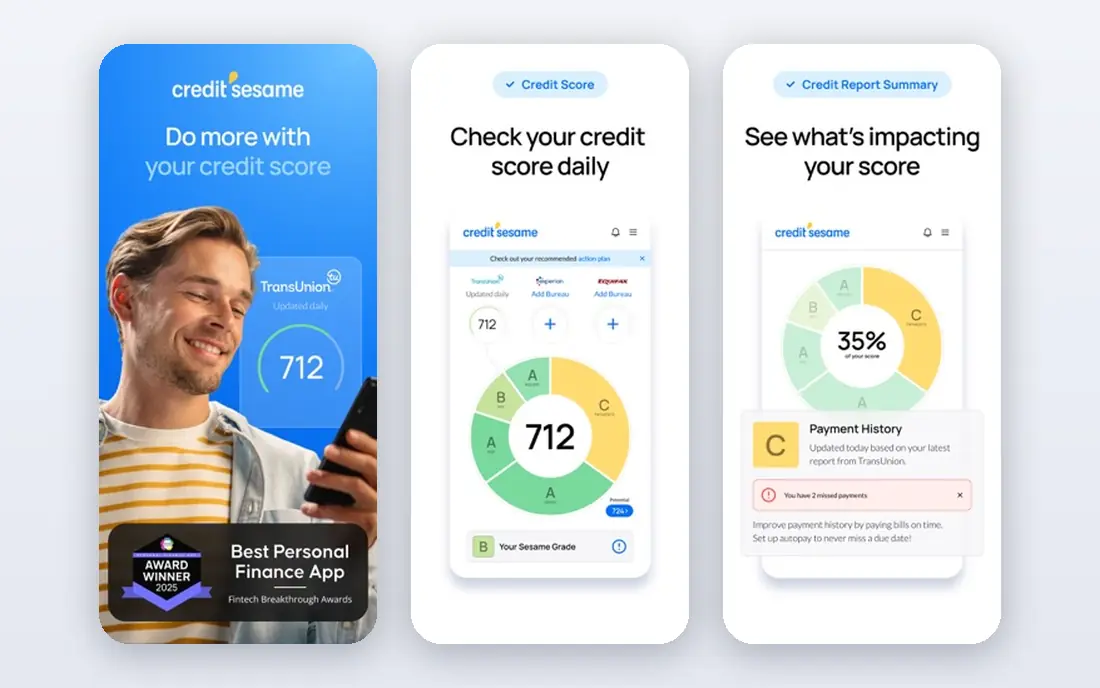
Credit Sesame lists a free credit score refreshed daily, a weekly credit report summary with a Sesame Grade, and free credit alerts and monitoring. The listing says alerts cover changes in your credit report in real time.
A premium subscription adds three-bureau credit scores, a score simulator, credit dispute support, rent reporting and instant credit offers. We could not open the pricing page, so the premium price is marked See website.
It is a reasonable second app if you want a different score view. The iOS app has a 4.8 rating from more than 430,000 ratings.
- Free score refreshed daily and free alerts
- Weekly credit report summary with a letter grade
- Premium adds three-bureau scores and dispute support
- Premium price not found
- Several features are behind the paid plan
How we picked these
We checked each company's official site, pricing page or App Store listing, and we did not claim hands-on testing. For each service we recorded which bureaus it watches, which score model it uses, what alerts you get, and what the free plan leaves out. Prices are only listed where an official page stated them.
We did not rank by popularity or affiliate commissions. Several of these companies earn money from offers, so we noted that when the company said so.
What to know before you choose a service
Credit monitoring tells you something changed. It does not stop anyone from opening an account.
Free monitoring is enough for most people
If you only need alerts about new accounts and inquiries, a free service such as Credit Karma, CreditWise or TransUnion covers the basics. Pay only if you need a different bureau, FICO versions, identity restoration or insurance.
Monitor more than one bureau
Credit Karma covers TransUnion and Equifax, CreditWise watches TransUnion and Experian changes, and Experian covers Experian. Using two free tools can cover all three bureaus, though scores differ by model.
Use a credit freeze for real protection
According to the FTC, placing or lifting a credit freeze costs nothing and does not affect your credit score. A freeze blocks new accounts from being opened in your name until you lift it. Pair a freeze with free monitoring and you have most of the protection a paid plan offers.
Frequently asked questions
What is the best credit monitoring service?
For most people, we would start with Credit Karma because it is free and watches two bureaus. If you want a FICO Score 8, CreditWise and Experian are free alternatives.
Is there a free credit monitoring service?
Yes. Credit Karma, CreditWise, TransUnion, Experian, NerdWallet and Credit Sesame all describe free monitoring. Each covers different bureaus, so compare them before choosing.
Is paid credit monitoring worth it?
It can be, if you want three-bureau monitoring, identity restoration or insurance in one plan. Aura, Equifax Complete Premier and myFICO bundle those features, but many of the alerts are available free elsewhere.
Does credit monitoring prevent identity theft?
No. It alerts you after something appears on your credit report. A credit freeze is what blocks new accounts, and monitoring will not catch things like bank withdrawals.
Does checking my own credit hurt my score?
The services we checked, including CreditWise, myEquifax and TransUnion, say checking your own credit does not hurt your score.
Sources
- https://www.creditkarma.com/credit-monitoring
- https://apps.apple.com/us/app/id519817714
- https://apps.apple.com/us/app/id1087101090
- https://apps.apple.com/us/app/id649008868
- https://www.equifax.com/personal/
- https://apps.apple.com/us/app/id6502468755
- https://apps.apple.com/us/app/id1008234539
- https://www.myfico.com/
- https://apps.apple.com/us/app/id714626557
- https://www.aura.com/
- https://www.aura.com/pricing
- https://apps.apple.com/us/app/id1174471607
- https://apps.apple.com/us/app/id476718980
- https://consumer.ftc.gov/articles/credit-freezes-and-fraud-alerts