Best Day Trading Platform for Beginners in 2026: 8 Platforms Compared

- Our pick for most people is Webull, because it balances price, features and ease of use for the widest group of readers.
- Free plans are real here, but the limits matter: check what Fidelity and Charles Schwab actually include before you commit.
- Prices in this guide come from vendor pricing pages and current comparisons checked in October 2026, and they can change, so confirm the plan on the vendor site before you buy.
- The best choice depends on your budget, your experience level and how much support you want, not on which brand is most famous.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
 Webull | Learning active trading with paper trading | Free | Yes | Visit |
 Fidelity | Best overall for US beginners | Free | Yes | Visit |
 Charles Schwab | Education and practice trading | Free | Yes | Visit |
 Robinhood | Simple mobile trading for beginners | Free | Yes | Visit |
 E*TRADE | Beginner traders who want practice plus research | Free | Yes | Visit |
 SoFi Invest | Simple investing plus automated portfolios | Free | Yes | Visit |
 Interactive Brokers | Ambitious beginners who want global access | Free | Yes | Visit |
 Public | Simple multi-asset investing with community | Free | Yes | Visit |
The best Day Trading Platform for Beginners in 2026
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews to build this list for best day trading platform for beginners. Every option below exists and works today, and each one earns its place for a different kind of reader.
Webull
Ideal for: Learning active trading with paper trading
Here is the short version. Webull is the strongest entry point for learning active trading, because paper trading with real-time prices lets beginners practise without risk. It fits readers who want learning active trading with paper trading, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The advanced tools can tempt overtrading, so set a practice period and a position-size rule before going live. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Paper trading with real-time pricing
- Advanced charting
- No commissions on stocks and options
- Less suited to simple retirement plans
- Margin rates vary
Fidelity
Ideal for: Best overall for US beginners
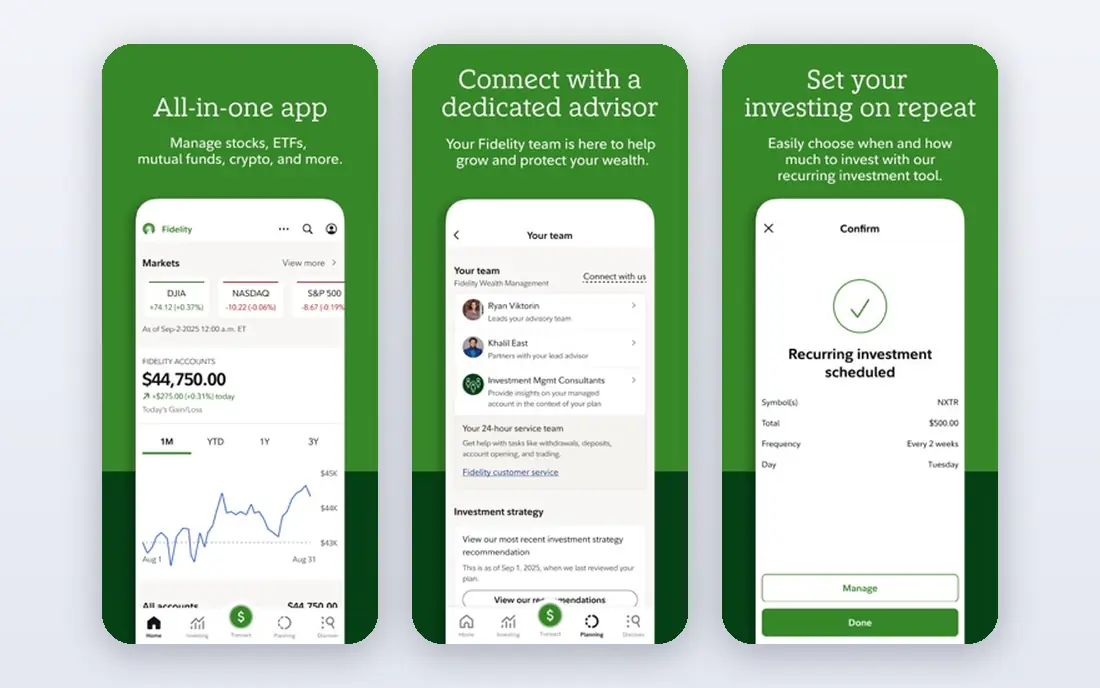
Start here if you want the safe default. Fidelity suits beginners who want education, support and a platform that grows from first trade to active trading. It fits readers who want best overall for us beginners, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The breadth takes time to learn, but starting with the basic app and adding Active Trader Pro later keeps it manageable. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Fractional shares from 1 dollar
- Extensive education
- Active Trader Pro
- Platform range can feel large at first
- Options tools are less specialised
Charles Schwab
Ideal for: Education and practice trading
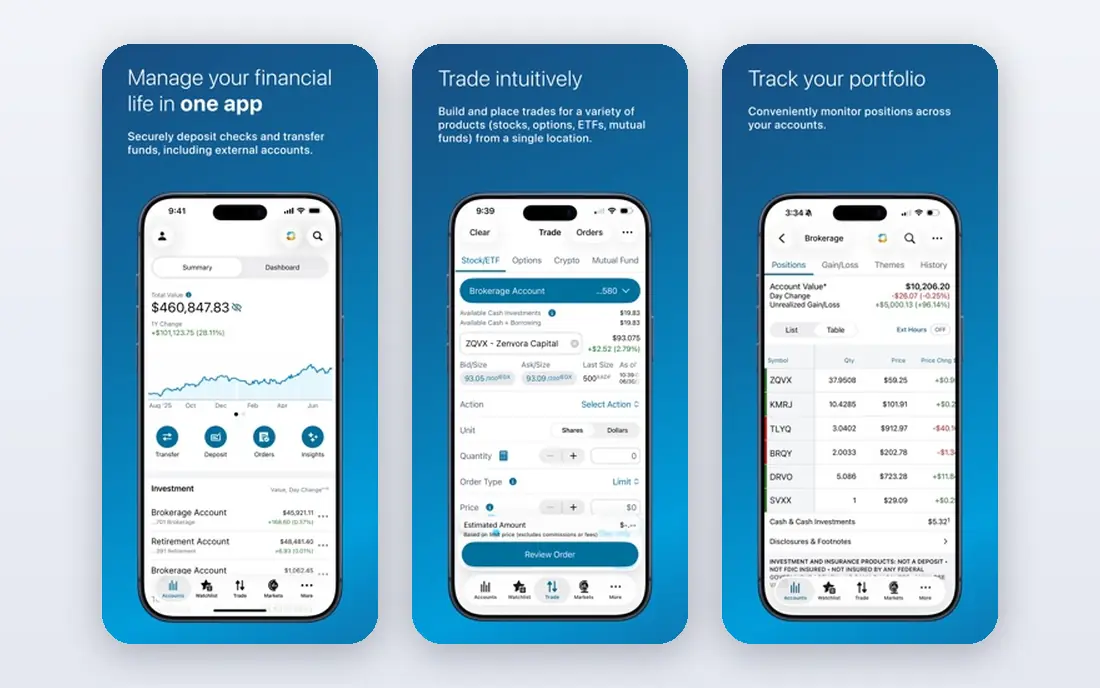
This one suits a specific kind of reader. Schwab suits beginners who want to practise seriously, because paperMoney mirrors real market data and tools. It fits readers who want education and practice trading, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Start with the basic Schwab app and open thinkorswim only when paper trading becomes your main learning tool. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Thinkorswim paperMoney
- Strong education
- Banking beside investing
- Thinkorswim learning curve is steep
- Range can overwhelm new traders
Robinhood
Ideal for: Simple mobile trading for beginners
Consider this if the top picks do not fit. Robinhood is the easiest first app, with fractional shares and a clean interface that hides market complexity. It fits readers who want simple mobile trading for beginners, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. That simplicity is also the risk, since frequent trading hurts returns, so use it for steady learning, not daily speculation. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Simplest mobile experience
- Fractional shares
- No commissions
- Interface can encourage frequent trading
- Research is thin
E*TRADE
Ideal for: Beginner traders who want practice plus research
A strong option for a narrower need. E*TRADE suits beginners who want practice accounts and research beside trading. It fits readers who want beginner traders who want practice plus research, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Fractional share limits matter for small accounts, so check your favourite stocks before opening an account. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Practice trading
- Good research
- Power E*TRADE tools
- Platform is being integrated into Morgan Stanley
- Fractional limits apply
SoFi Invest
Ideal for: Simple investing plus automated portfolios
Worth a close look before you decide. SoFi Invest suits beginners who want a simple start with both self-directed and automated options. It fits readers who want simple investing plus automated portfolios, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Active day traders will outgrow it, but for learning the basics it is friendly and low pressure. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Fractional investing from 5 dollars
- Self-directed and automated accounts
- Banking in one app
- Research tools are lighter than specialists
- Fewer advanced trading features
Interactive Brokers
Ideal for: Ambitious beginners who want global access
This belongs on the shortlist for a reason. Interactive Brokers suits ambitious beginners who plan to trade globally and want low costs. It fits readers who want ambitious beginners who want global access, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Most beginners should start with Fidelity or Schwab and move here only when the extra markets matter. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Global market access
- Low costs
- IBKR Lite for US beginners
- Steep learning curve
- Platform assumes knowledge
Public
Ideal for: Simple multi-asset investing with community
Do not overlook this one. Public suits beginners who want simple multi-asset investing with recurring plans and a community feel. It fits readers who want simple multi-asset investing with community, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Check fees on subscriptions and asset types before relying on it as a sole platform. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Stocks, ETFs, bonds and Treasuries
- Recurring plans
- Community features
- Some subscriptions and asset types carry separate fees
- No mutual funds
How we picked these
We started from official feature pages and pricing pages, then checked app store listings, privacy policies and public reviews to confirm each product still works and still fits the topic. Products that could not be verified, or that only partly matched the topic, were left out, even when they were well known. We favoured a mix of established leaders and strong smaller options, and we weighted price transparency, a usable free tier or trial, and honest limits more heavily than marketing claims. No product on this list paid for its place, and our pick for most people is the one we would suggest to a friend with ordinary needs and an ordinary budget.
How to choose a day trading platform as a beginner
Start with paper trading, because practising with virtual money is the cheapest education in trading. Next, check education and support, since a platform with clear lessons and reachable help beats a cheaper platform that leaves you alone. Then check costs that actually apply: commissions are zero at most firms, but margin rates, regulatory fees and data subscriptions still matter. This is not financial advice, and day trading carries real risk, including losing money quickly, so only trade with money you can afford to lose, keep position sizes small, and learn risk management before using borrowed money. Also check the pattern day trader rule: four or more day trades in five business days in a margin account needs at least 25,000 dollars in equity, or your account faces restrictions. Also check whether the platform encourages or restrains frequent trading, because an interface built for speed can hurt a beginner. Set a daily loss limit, a maximum number of trades, and a rule to stop after two losses in a row. The best beginner platform is the one that helps you learn slowly, not the one that helps you trade fastest.
Frequently asked questions
What is the best day trading platform for beginners?
Webull and Fidelity Active Trader Pro are the strongest entry points, thanks to paper trading and education. Schwab paperMoney suits serious practice, while Robinhood suits simple mobile trading.
What is the best day trading app for beginners?
Robinhood is the simplest mobile app, Webull offers the best paper trading and charting for learners, and Fidelity offers the best all-round beginner experience with education.
Can beginners day trade with little money?
Yes, fractional shares and no commissions let beginners start small, but the pattern day trader rule limits margin accounts under 25,000 dollars to fewer than four day trades in five business days. Cash accounts have different limits.
Is day trading risky for beginners?
Yes, day trading can lose money quickly, especially with borrowed money or options. Paper trading, small positions and strict loss limits reduce risk, but they do not remove it.
Do I need 25,000 dollars to day trade?
Only for unlimited day trading in a margin account under the pattern day trader rule. Cash accounts and fewer trades avoid that threshold, but settlement rules still limit how fast you can reuse funds.