Best Debt Payoff App in 2026: 8 Options Compared

- 1
 Undebt.itFree debt payoff planningVisit
- 2
 Debt Payoff PlannerSimple payoff calculator appVisit
- 3
 YNABBudgeting that supports payoffVisit
- 4
 EveryDollarSimple Ramsey-style budgetingVisit
- 5
 Rocket MoneyBills and subscription trackingVisit
- Undebt.it is our first pick for most people, because it covers free debt payoff planning with a clear set of features and a straightforward setup.
- If you want to start free, look at Undebt.it, Debt Payoff Planner, EveryDollar, which all offer a free plan or a free core product.
- Goodbudget is worth a look when the bigger names feel too broad, since it focuses on envelope budgeting.
- Prices and plan limits change often, so check the official pricing page for the product you shortlist before you pay.
- The right choice depends on your budget, your current tools and how much setup help you want, not on the longest feature list.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Undebt.it | Free debt payoff planning | Free | Yes | Visit |
| Debt Payoff Planner | Simple payoff calculator app | Free | Yes | Visit |
| YNAB | Budgeting that supports payoff | See website | Free trial | Visit |
| EveryDollar | Simple Ramsey-style budgeting | Free | Yes | Visit |
| Rocket Money | Bills and subscription tracking | Free | Yes | Visit |
 Monarch Money | Full money tracking | See website | Free trial | Visit |
 PocketSmith | Forecasting and payoff planning | See website | Free trial | Visit |
 Goodbudget | Envelope budgeting | Free | Yes | Visit |
The best debt payoff app
These 8 options cover the main ways people approach debt payoff app. We compared official feature pages, pricing, app-store listings, privacy policies and public reviews to sort out where each one earns its place, and where it falls short. This is not financial advice. Prices, returns and risks vary, so check the official terms and consider independent advice before you commit money.
Undebt.it
Ideal for: Free debt payoff planning
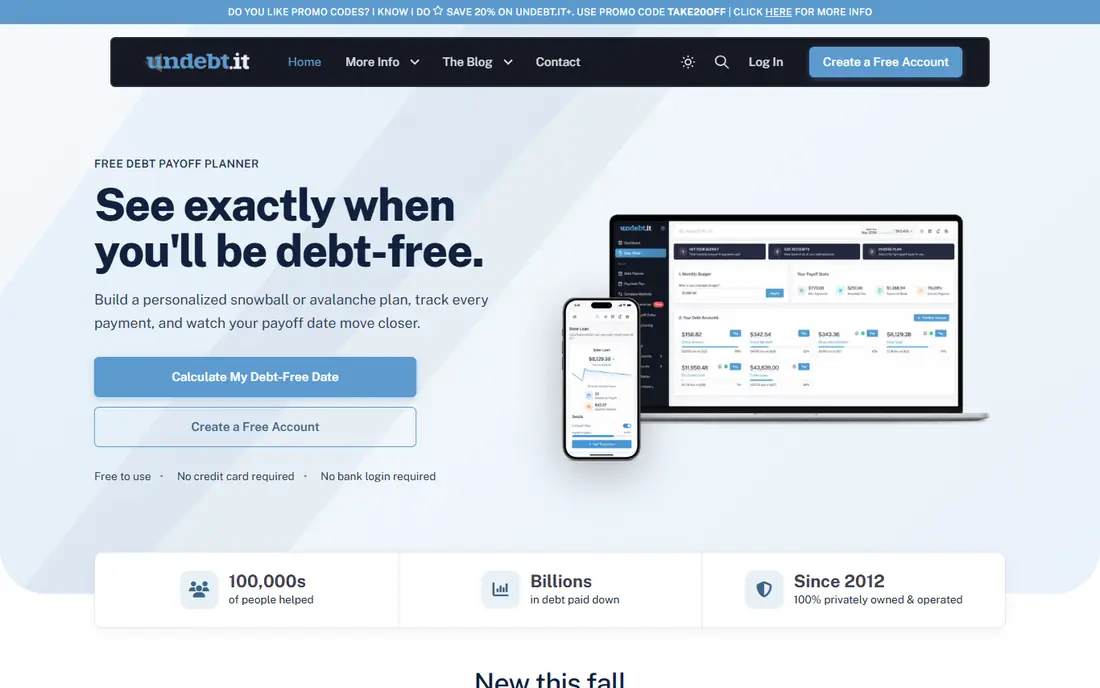
Undebt.it stands out for free debt payoff planning. Undebt.it is the best free way to plan a payoff order. Its strengths include free snowball and avalanche plans; payoff tracking; simple design, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is no bank sync on free plan; interface is basic. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Free snowball and avalanche plans
- Payoff tracking
- Simple design
- No bank sync on free plan
- Interface is basic
Debt Payoff Planner
Ideal for: Simple payoff calculator app
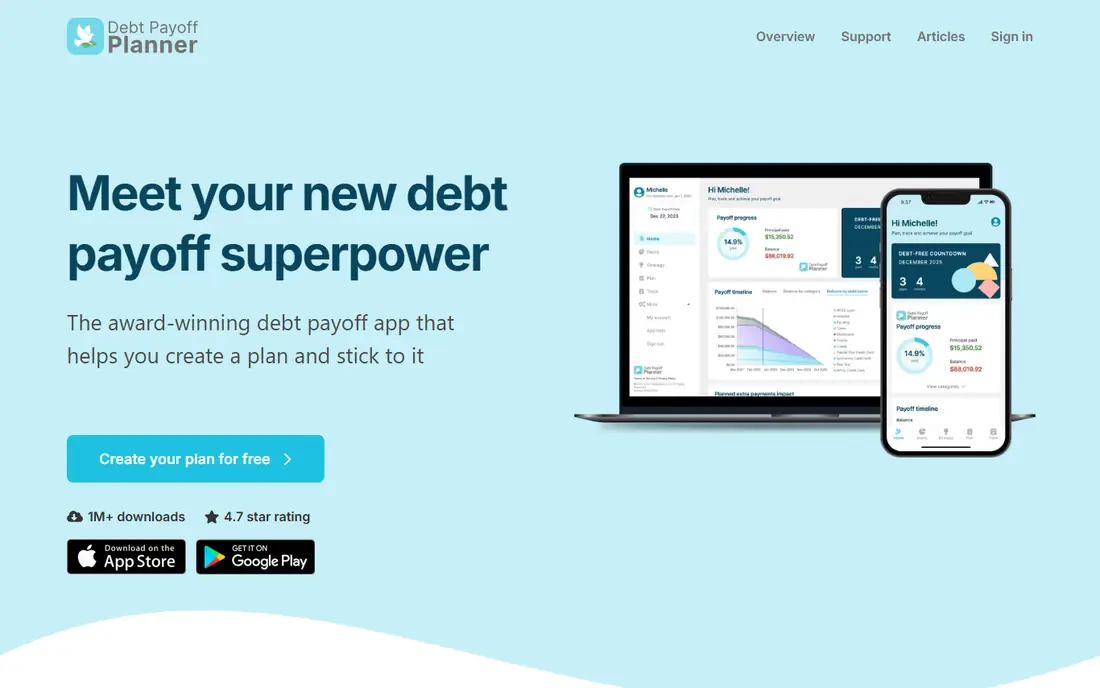
For simple payoff calculator app, Debt Payoff Planner is a name worth shortlisting. Debt Payoff Planner fits people who want a simple, focused app. Its strengths include simple payoff plans; extra payment tracking; clear progress, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is bank sync is limited; design is basic. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Simple payoff plans
- Extra payment tracking
- Clear progress
- Bank sync is limited
- Design is basic
YNAB
Ideal for: Budgeting that supports payoff
YNAB earns its place here for budgeting that supports payoff. YNAB suits people who want payoff inside a full budget system. Its strengths include strong budgeting method; goal tracking; education, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is subscription cost; learning curve. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Strong budgeting method
- Goal tracking
- Education
- Subscription cost
- Learning curve
EveryDollar
Ideal for: Simple Ramsey-style budgeting
If simple Ramsey-style budgeting is your main need, start with EveryDollar. EveryDollar fits fans of simple, zero-based budgeting. Its strengths include simple budgets; debt tracking; Ramsey method links, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is bank sync needs premium; features are basic. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Simple budgets
- Debt tracking
- Ramsey method links
- Bank sync needs premium
- Features are basic
Rocket Money
Ideal for: Bills and subscription tracking
Rocket Money stands out for bills and subscription tracking. Rocket Money helps people free up cash by cutting bills first. Its strengths include finds subscriptions; bill tracking; budgeting tools, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is payoff planning is indirect; premium costs. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Finds subscriptions
- Bill tracking
- Budgeting tools
- Payoff planning is indirect
- Premium costs
Monarch Money
Ideal for: Full money tracking
For full money tracking, Monarch Money is a name worth shortlisting. Monarch suits households that want full money tracking with payoff goals. Its strengths include account sync; goals; cash flow views, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is subscription cost; payoff tools are part of wider budgeting. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Account sync
- Goals
- Cash flow views
- Subscription cost
- Payoff tools are part of wider budgeting
PocketSmith
Ideal for: Forecasting and payoff planning
PocketSmith earns its place here for forecasting and payoff planning. PocketSmith fits planners who want to forecast payoff dates. Its strengths include cash flow forecasts; payoff scenarios; bank feeds, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is learning curve; price tiers matter. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Cash flow forecasts
- Payoff scenarios
- Bank feeds
- Learning curve
- Price tiers matter
Goodbudget
Ideal for: Envelope budgeting
If envelope budgeting is your main need, start with Goodbudget. Goodbudget suits couples and households using envelope budgeting. Its strengths include envelope method; shared budgets; simple design, which is why it keeps appearing in comparisons of debt payoff app. In daily use, the balance of features and price matters more than any single headline feature, and this option scores well on that balance for its target users. The honest catch is bank sync is limited; interface is basic. That trade-off will matter more to some buyers than others, so weigh it against what you actually need each week. If the catch touches your main use case, move on to the next option rather than hoping a later update fixes it. Our pick for most people is the option whose strengths match the job at hand and whose weaknesses sit outside it.
- Envelope method
- Shared budgets
- Simple design
- Bank sync is limited
- Interface is basic
How we picked these
We started from the topic itself, best debt payoff app, and shortlisted products that exist, work in October 2026 and truly fit that topic. We checked official feature pages and pricing pages, app-store listings where relevant, privacy policies and public reviews, and we dropped anything we could not verify or that only loosely matched the topic. We favored a mix of well-known leaders and strong smaller options, and we weighed who each product really serves, what it does well, what it costs and where it falls short. We did not claim hands-on testing that did not happen, and we wrote See website wherever a price could not be verified from the vendor.
Choosing the right debt payoff app for you
Price and features only tell part of the story. The sections below cover the practical checks that help you pick well among debt payoff app, without spending weeks on research.
Start with your main job
Write down the one job this product must do well, then judge every option against that job first. A long feature list means little if the core job feels slow, confusing or unreliable in daily use.
Check the price over a year
Monthly prices hide the real cost, so add up a full year, including add-ons, seat counts and any fees at renewal. A cheaper monthly plan can cost more once the features you need sit in a higher tier.
Test the free plan or trial
Use a free plan or trial with a real task from your own work, not just a quick tour of the interface. That test shows whether setup, support and daily use fit your team before you commit.
Read the fine print before you commit
Check contract length, renewal terms, cancellation steps and what happens to your data if you leave. Clear terms are a good sign, and vague terms are a reason to ask questions before you pay.
Frequently asked questions
Which debt payoff app is best for beginners?
Start with Undebt.it, since it covers free debt payoff planning with a straightforward setup. If you want a simpler start, Debt Payoff Planner is also easy to learn. Try a free plan or trial first, and judge it on a real task from your own work.
Is there a free debt payoff app option?
Yes, Undebt.it, Debt Payoff Planner, EveryDollar all offer a free plan or a free core product, though paid tiers add features and limits are higher. Free plans suit testing and light use, while heavier use usually needs a paid plan.
How much do debt payoff app cost?
Prices vary widely, and many vendors quote by plan, seats or usage, so we wrote See website wherever a price could not be verified. Compare a full year of cost, including add-ons and renewal prices, rather than the first-month headline price.
How do I choose between these debt payoff app?
Start with your main job, then shortlist two or three options that fit it, including Undebt.it and YNAB. Test each one with a real task, check the fine print on renewal and cancellation, and pick the one whose weaknesses sit outside your main use.
Can I switch later if I pick the wrong one?
In most cases yes, but switching costs time, especially if you have stored data, trained a team or built workflows around one product. Before you commit, check how to export your data and cancel, so a later move stays possible.