For banking and payments API integration, Decentro is where this list starts. HyperVerge is better for passive liveness and face authentication, and Setu is better for KYC and credit infrastructure APIs. The remaining 2 options are covered below with prices and limits.
Choosing digital onboarding software for NBFCs usually comes down to price, fit and limits. This Ainotely guide sets 5 tools side by side on those three points, with the facts kept short and checkable.
Key takeaways
Decentro takes the first slot, best suited to banking and payments API integration.
A permanent free plan is missing from all 5 tools, Decentro and Jumio included; plan for a trial or a premium start.
For identity verification with AML screening, Jumio is worth a look.
One limit worth knowing about HyperVerge: narrower than full onboarding suites.
Decentro targets banking and payments API integration. Since Decentro is API-first, it assumes development capacity and does not replace identity verification or AML screening on its own.
In practice, Decentro gives you APIs and SDKs for building, launching and scaling fintech products, with automatic APIs for payments and banking integrations plus open banking connectivity. Check the vendor site for Decentro pricing; none is listed in this comparison. Trial and free access: Not stated.
Best for: Passive liveness and face authentication
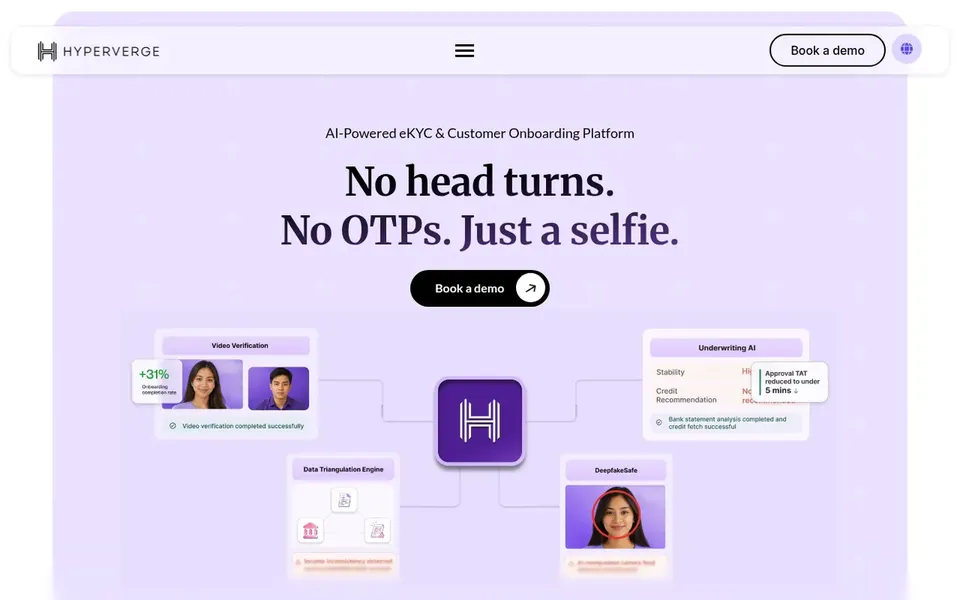
HyperVerge serves passive liveness and face authentication. Choose it when liveness and document extraction are the core problem, and pair it with other tools for the rest of the journey.
Trade-offs to know: Document coverage varies by market.
HyperVerge is more of a verification specialist than a complete onboarding product, so NBFCs still need workflow, screening or banking integrations elsewhere. It also gives you OCR for bank statements and payslips across global markets, which helps NBFCs that assess income documents. Check the vendor site for HyperVerge pricing; none is listed in this comparison. Free access: Free trial.
Setu serves KYC and credit infrastructure APIs. Setu offers APIs for identity verification, onboarding, Account Aggregator, UPI collections and Bharat Connect, positioned as infrastructure for India's digital economy. Also, Setu is infrastructure, so the onboarding experience, compliance logic and support layers are mostly yours to build.
Teams seeking a managed end-to-end onboarding product may have to combine Setu with verification and workflow vendors. NBFCs can use these building blocks to link verification, data sharing and collections within their own onboarding flows. Setu does not show a starting price in this comparison, so check the vendor site for current pricing. Trial and free access: Not stated.
Where it shines: UPI collections and payment APIs. Drawbacks to consider: Developer integration required.
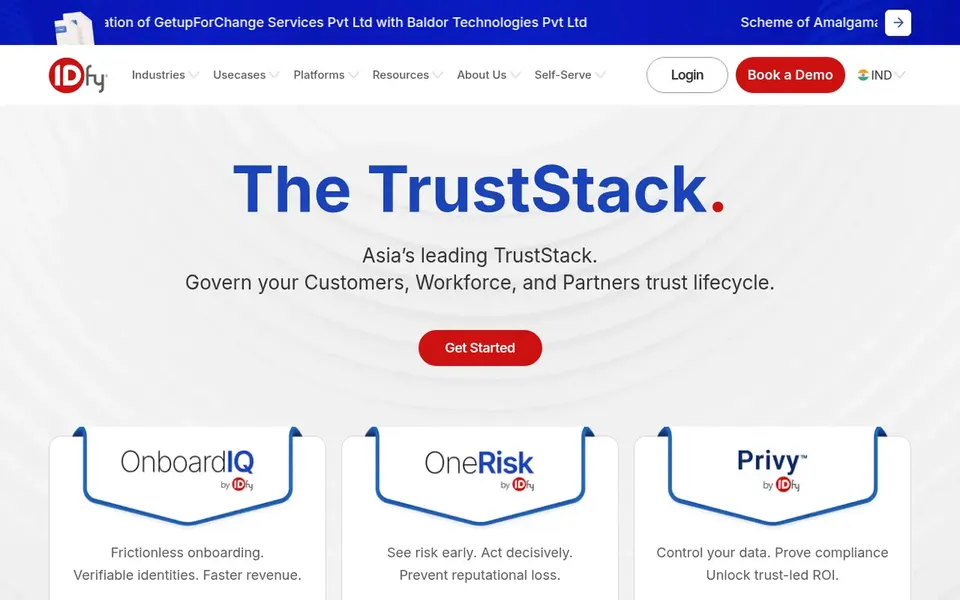
IDfy is designed for end-to-end onboarding and compliance. For a NBFC, that means identity checks, onboarding flows and compliance tooling can sit in one place instead of being stitched together. Since IDfy spans multiple product areas, teams should map which modules they actually need before committing.
More specifically, IDfy presents itself as a TrustStack for secure customer onboarding and smarter fraud detection, with privacy governance geared toward banks and other regulated sectors. For everyday use, smaller NBFCs with narrow onboarding requirements may find a focused point option more straightforward, whereas those needing fraud and compliance coverage together will get more from the broader stack. Check the vendor site for IDfy pricing; none is listed in this comparison. Free plan details: Not stated.
What to check first: Depth varies by product module.
Best for: Identity verification with AML screening
Jumio is built with identity verification with AML screening in mind. For NBFCs, this supports both onboarding checks and continuing fraud and compliance monitoring.
What to check first: Screening setup relies on jurisdiction.
More specifically, Jumio describes an identity verification and intelligence system that goes beyond one-time ID checks, adding risk signals and AML screening powered by its Identity Graph. The system is verification-focused, so onboarding workflow, document analysis and banking connections may still come from other vendors. No starting price is listed for Jumio here; confirm pricing on the vendor site. Trial and free access: Not stated.
Request quotes from Decentro, Jumio and the others; the list shows no fixed prices.
Take the trial from HyperVerge and push a live task through it before you pay.
Before choosing Decentro, weigh its main limit: needs developer resources.
Involve the people who will use HyperVerge daily; a short pilot beats a long feature checklist.
Find out what support IDfy includes on your plan, and whether onboarding help costs extra.
How we picked
Selection started from tools commonly considered for digital onboarding software for NBFCs, then narrowed to 5 that have clear pricing information or a clear quote process. Where a price is missing, the vendor does not list one publicly or ties it to a quote. Always confirm before budgeting. The ranking is editorial: typical fit first, then clear pricing, then free access. If your needs are unusual, read the profiles rather than relying on position.
Every price and plan detail on this page comes from the vendors’ own websites. We did not run hands-on tests unless the text says so, and we do not publish star ratings or review scores. See how we score and our disclosure.
Keep your shortlist in one place
Paste prices, trial dates and notes from this guide into Ainotely, our AI note app. It files them into a topic and pulls out tasks like “cancel trial by Friday”. Free 7-day trial, no card needed.
What should a NBFC look for in onboarding software?
Prioritize identity verification, fraud and AML screening, document handling and privacy compliance, then check how these link to your credit origination systems. Confirm integration choices and data residency before shortlisting.
Is Decentro the right pick for everyone comparing digital onboarding software for NBFCs?
No single tool suits every team. Decentro comes first because it fits banking and payments API integration, while HyperVerge suits passive liveness and face authentication and Setu suits KYC and credit infrastructure APIs. Match the tool to your own size, budget and workflow before deciding.
Can I try these tools before paying?
Often, yes. HyperVerge offers a free trial. Use your own data and a real task during the test, and check what the free tier or trial limits before you rely on it.
Do these tools publish their prices?
No. None of the tools, from Decentro to Jumio, shows a fixed starting price here, so budget time for quotes.
Does any tool for digital onboarding software for NBFCs here have a free plan?
A permanent free plan is not offered by Decentro, Jumio or the other tools here. HyperVerge offer a trial. Plan a short evaluation period instead.