Best Investment Companies in 2026: 8 Companies Compared

- Our pick for most people is Fidelity, because it balances price, features and ease of use for the widest group of readers.
- Free plans are real here, but the limits matter: check what Charles Schwab and Vanguard actually include before you commit.
- Prices in this guide come from vendor pricing pages and current comparisons checked in October 2026, and they can change, so confirm the plan on the vendor site before you buy.
- The best choice depends on your budget, your experience level and how much support you want, not on which brand is most famous.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
 Fidelity | Best overall brokerage for most investors | Free | Yes | Visit |
 Charles Schwab | Full-service investing with thinkorswim | Free | Yes | Visit |
 Vanguard | Buy-and-hold index investors | Free | Yes | Visit |
 E*TRADE | Options and active traders inside Morgan Stanley | Free | Yes | Visit |
 Robinhood | Simple mobile investing for beginners | Free | Yes | Visit |
 Interactive Brokers | Global investors and advanced traders | Free | Yes | Visit |
 SoFi Invest | Beginners who want investing plus banking | Free | Yes | Visit |
 Betterment | Hands-off diversified portfolios | $4 per month | No | Visit |
The best Investment Companies in 2026
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews to build this list for best investment companies. Every option below exists and works today, and each one earns its place for a different kind of reader.
Fidelity
Ideal for: Best overall brokerage for most investors
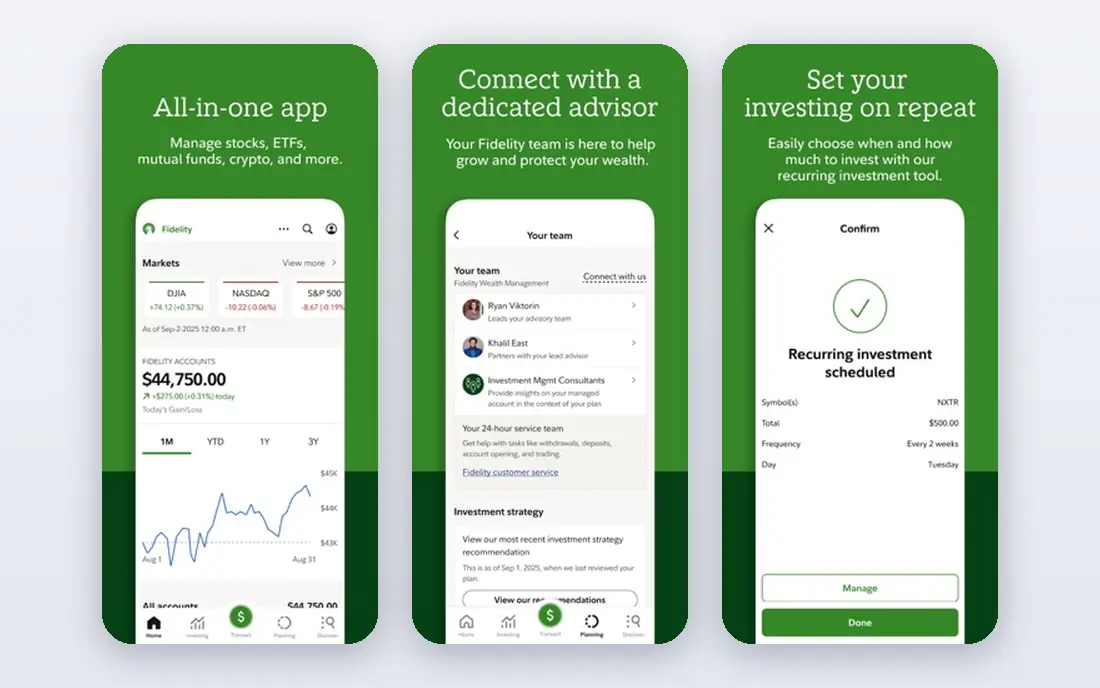
Here is the short version. Fidelity is the default recommendation for most investors, because it combines zero commissions, no account minimums and index funds with no expense ratio. It fits readers who want best overall brokerage for most investors, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The zero-fee funds are Fidelity-only, so investors who value portability should use ETFs instead, but for most long-term accounts that trade-off is minor. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Zero-commission stock and ETF trades
- Zero-expense index funds
- Strong research and support
- Zero-expense funds cannot transfer elsewhere without selling
- Platform can feel large
Charles Schwab
Ideal for: Full-service investing with thinkorswim
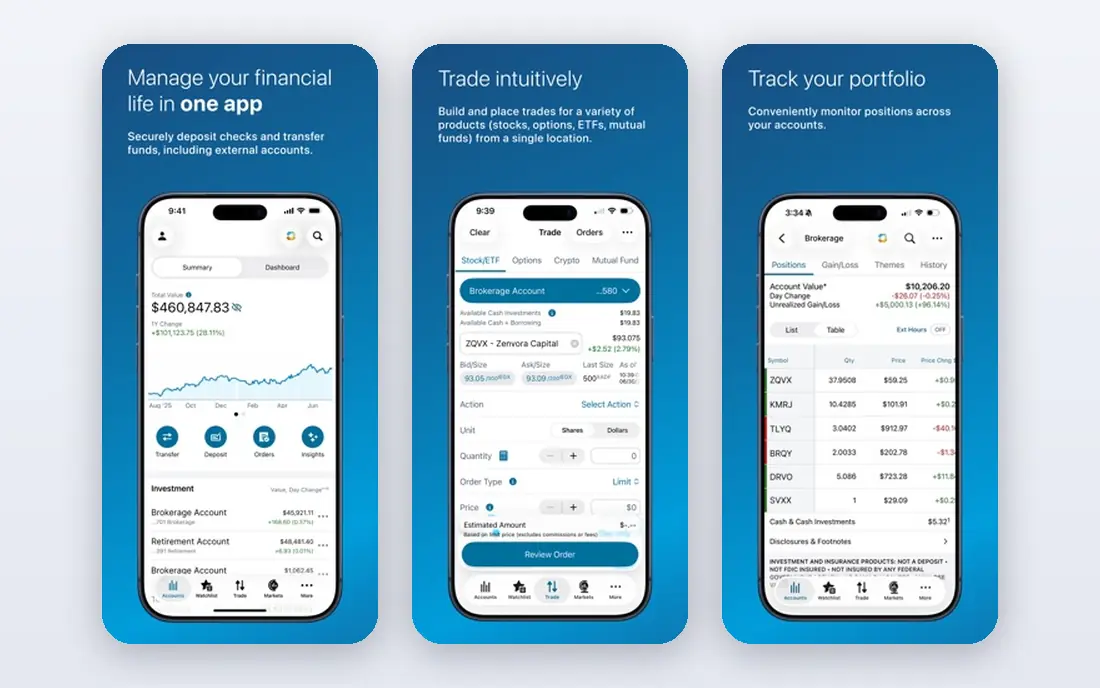
Start here if you want the safe default. Schwab suits investors who want a full-service firm plus a serious trading platform, with branches, banking and retirement accounts under one roof. It fits readers who want full-service investing with thinkorswim, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The breadth can overwhelm a first account, so start with the basic brokerage view and open thinkorswim only when you need its tools. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Zero-commission trades
- Thinkorswim platform
- Banking and checking in one place
- Platform range can feel complex at first
- Some index funds cost slightly more than Fidelity
Vanguard
Ideal for: Buy-and-hold index investors
This one suits a specific kind of reader. Vanguard remains the home of patient index investing, with low-cost funds and a structure built around investor ownership. It fits readers who want buy-and-hold index investors, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The platform is plainer than Fidelity or Schwab, and customer service can be slower, but buy-and-hold investors rarely need daily hand-holding. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Inventor of the index fund
- Low-cost ETFs such as VTI
- Strong retirement focus
- Some mutual funds need a 3,000 dollar minimum
- Platform feels plain next to rivals
E*TRADE
Ideal for: Options and active traders inside Morgan Stanley
Consider this if the top picks do not fit. ETRADE suits active traders who want Power ETRADE analytics inside a large firm, with research and retirement accounts beside trading. It fits readers who want options and active traders inside morgan stanley, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Fractional share limits matter for small accounts, so check whether your favourite stocks support fractional buys before you open an account. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Zero-commission stock and ETF trades
- Power E*TRADE tools
- Good research
- No fractional shares for all stocks
- Platform is being integrated into Morgan Stanley
Robinhood
Ideal for: Simple mobile investing for beginners
A strong option for a narrower need. Robinhood is the easiest on-ramp to investing, with fractional shares and a clean app that hides the complexity of markets. It fits readers who want simple mobile investing for beginners, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. The simplicity can encourage frequent trading, which hurts long-term returns, so use it for steady investing, not for chasing daily moves. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Simplest mobile experience
- Fractional shares from 1 dollar
- No commissions
- Research is thin
- Gold subscription needed for better margin rates and IRA match
Interactive Brokers
Ideal for: Global investors and advanced traders
Worth a close look before you decide. Interactive Brokers suits investors who trade beyond the United States or want the lowest costs on complex orders. It fits readers who want global investors and advanced traders, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Beginners should start elsewhere, because the platform assumes knowledge, but experienced traders will find depth rivals cannot match. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Access to global markets
- Low costs for active traders
- Strong tools
- Complex platform
- Lite and Pro pricing needs reading before you choose
SoFi Invest
Ideal for: Beginners who want investing plus banking
This belongs on the shortlist for a reason. SoFi Invest suits beginners who want investing, banking and automated portfolios in one app without juggling several logins. It fits readers who want beginners who want investing plus banking, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is free, with a free plan status of yes. Serious traders will outgrow its tools, but for a first portfolio and steady contributions it is a friendly place to start. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Fractional investing from 5 dollars
- Automated and self-directed accounts
- Banking in one app
- Research tools are lighter than specialists
- Fewer advanced trading features
Betterment
Ideal for: Hands-off diversified portfolios
Do not overlook this one. Betterment suits investors who want a diversified portfolio managed for them, with goals and rebalancing handled automatically. It fits readers who want hands-off diversified portfolios, and its published feature set matches that promise rather than trying to cover every possible use case at once. When we weighed it against the rest of this list, the balance of price, scope and support stood out for that group. The price picture is $4 per month, with a free plan status of no. The fee matters on small balances, so compare it with a free index fund portfolio before you commit, especially if you enjoy managing your own investments. Before you sign up, check the current plan limits on the official site, because caps on users, usage or features are where most buyers get surprised after the first month.
- Automated diversified portfolios
- Goal-based planning
- Tax-loss harvesting on higher tiers
- Monthly fee for small balances
- Less control than a self-directed brokerage
How we picked these
We started from official feature pages and pricing pages, then checked app store listings, privacy policies and public reviews to confirm each product still works and still fits the topic. Products that could not be verified, or that only partly matched the topic, were left out, even when they were well known. We favoured a mix of established leaders and strong smaller options, and we weighted price transparency, a usable free tier or trial, and honest limits more heavily than marketing claims. No product on this list paid for its place, and our pick for most people is the one we would suggest to a friend with ordinary needs and an ordinary budget.
How to choose an investment company for the long term
Start with cost, but measure the right cost. Commissions are now zero at most firms, so the real costs are fund expense ratios, margin rates, advisory fees and the price of features you actually use. Next, check account types: IRAs, Roth IRAs, taxable accounts and custodial accounts matter more over decades than a slick app. Then look at the investing style you will follow: index investors need low-cost funds, active traders need tools and data, and hands-off investors need automation. This is not financial advice, and investing carries risk, including the risk of losing money, so diversify, keep costs low and avoid putting money you need soon into the stock market. Also check customer support and platform stability, because you will need help rarely but urgently when markets fall. A firm with branches suits some investors, while a mobile-first firm suits others. Open the account that fits your plan, set up automatic contributions, and resist the urge to trade on headlines.
Frequently asked questions
What is the best investment company?
Fidelity is the best overall choice for most investors, Schwab suits full-service investors and active traders, and Vanguard suits buy-and-hold index investors. Robinhood and SoFi suit beginners who want simplicity.
Which investment company has the lowest fees?
Fidelity offers zero-expense index funds, while Vanguard and Schwab charge very low expense ratios on their index funds and ETFs. All three charge zero commission on stock and ETF trades.
What is the best investment company for beginners?
Fidelity, Schwab and SoFi are strong beginner choices, thanks to education, fractional shares and no account minimums. Robinhood is simpler but offers thinner research.
Do I need a lot of money to start investing?
No, most firms have no account minimum, and fractional shares let you start with 1 dollar at Fidelity and Robinhood or 5 dollars at SoFi. Regular small contributions matter more than a large first deposit.
Is my money safe with an investment company?
SIPC protects cash and securities up to 500,000 dollars, including a 250,000 dollar cash limit, if a member firm fails. It does not protect against market losses, so your investments can still fall in value.