Best IRA Companies in 2026: 8 Options Compared

- 1
 Fidelity InvestmentsBest overall IRAVisit
- 2
 Charles SchwabService and researchVisit
- 3
 VanguardLow-cost index investingVisit
- 4
 BettermentAutomated IRA investingVisit
- 5
 SoFiSimple app-based IRAVisit
- Our pick for most people is Fidelity Investments, because it covers the core needs of this category well without the highest price or the steepest learning curve.
- The cheapest way to start is often Charles Schwab or a free tier, but check what the free plan actually allows before you rely on it for daily work.
- Prices and free tiers change often, so confirm the current plan on the official site before you pay, especially for per-user and per-seat pricing.
- The best choice depends on your main use case, not on the longest feature list, so shortlist two options and trial them with a real task.
- Note: This is not financial advice. Investing carries risk, including loss of principal, and tax rules depend on your income and filing status. Consider speaking to a qualified adviser before choosing an IRA.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Fidelity Investments | Best overall IRA | Free | Yes | Visit |
| Charles Schwab | Service and research | Free | Yes | Visit |
| Vanguard | Low-cost index investing | Free | Yes | Visit |
| Betterment | Automated IRA investing | See website | Yes | Visit |
| SoFi | Simple app-based IRA | Free | Yes | Visit |
 E*TRADE | Education and mobile investing | Free | Yes | Visit |
 Merrill | Bank-linked IRA investing | Free | Yes | Visit |
 Wealthfront | Automated low-cost IRA | See website | Yes | Visit |
The best best ira companies
We compared official feature pages, pricing pages, app store listings, privacy policies, and public reviews to build this list. Each option below is a real product that works today, with a clear strength and an honest trade-off, so you can match the choice to your budget and your main task. Use the comparison table to shortlist, then read the full entries for the options that fit your situation.
Fidelity Investments
Ideal for: Best overall IRA
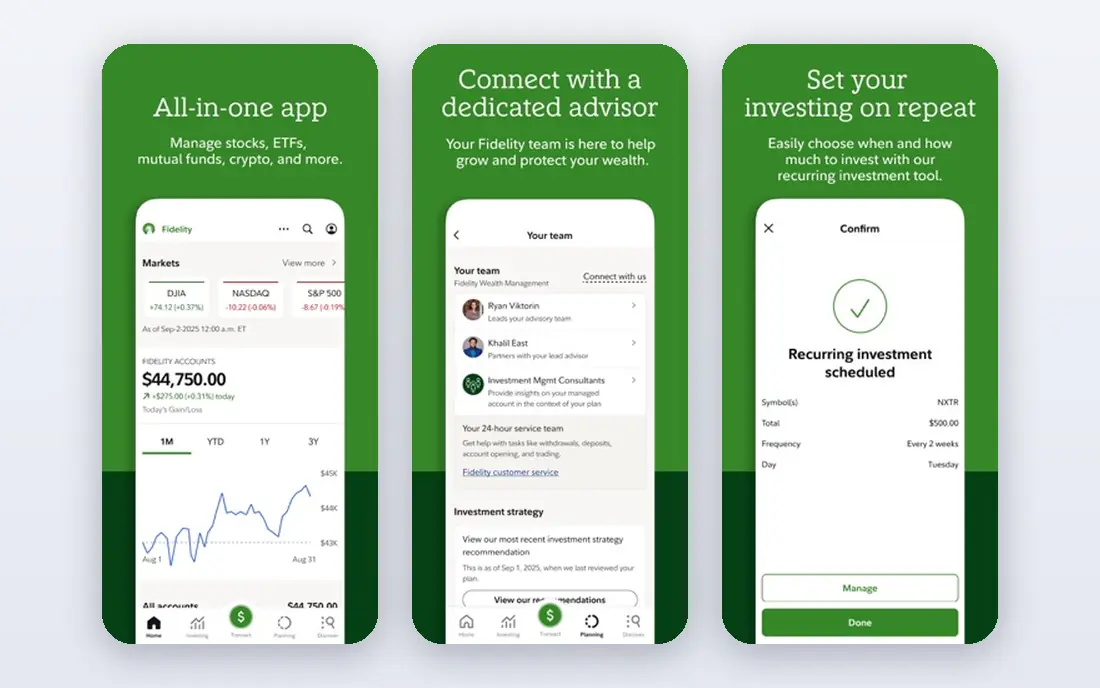
Fidelity is a frequent top pick for IRAs thanks to no minimum on many accounts, broad investment choice, and strong research. It suits beginners and experienced investors who want one account for stocks, ETFs, and funds. For someone whose main need is best overall ira, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: fund choices can overwhelm beginners; advice services cost extra. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- No account minimum for many IRAs
- Broad stocks, ETFs, and funds
- Strong research tools
- Fund choices can overwhelm beginners
- Advice services cost extra
Charles Schwab
Ideal for: Service and research
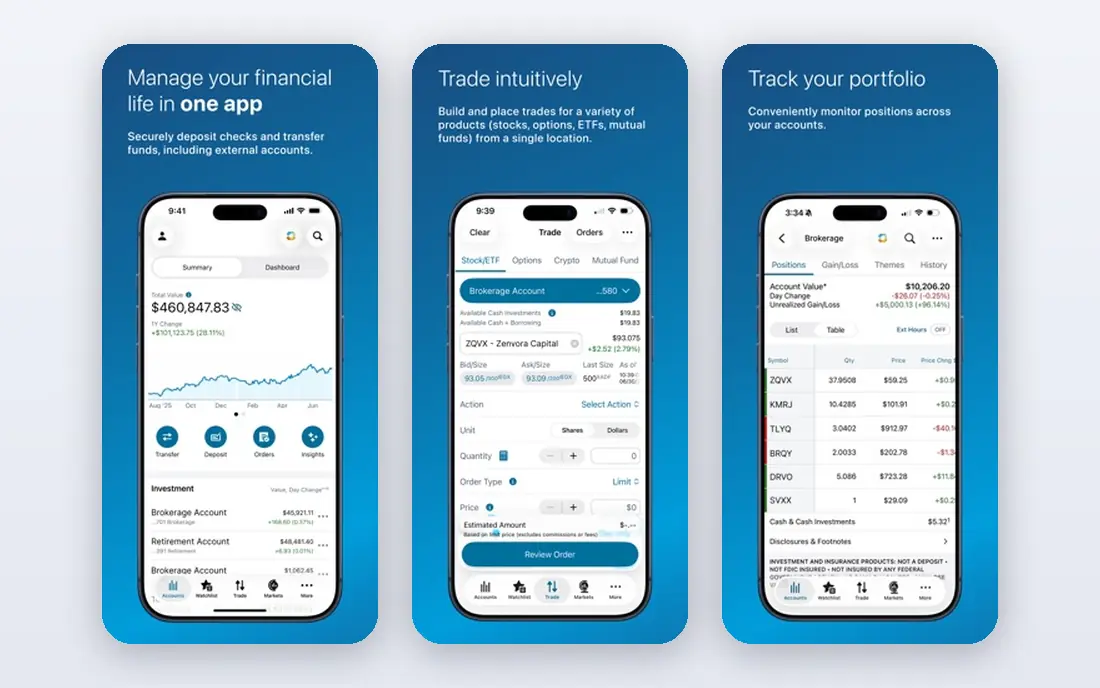
Charles Schwab offers IRAs with broad investment choice and well-regarded service and research. It suits investors who want help on the phone as well as a strong online platform. For someone whose main need is service and research, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: some funds carry minimums; interface has many features to learn. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- No account minimum for many IRAs
- Strong customer service
- Broad research
- Some funds carry minimums
- Interface has many features to learn
Vanguard
Ideal for: Low-cost index investing
Vanguard is built around low-cost index investing, with a broad fund and ETF lineup for long-term retirement savers. It suits investors who want to set a simple diversified portfolio and leave it alone. For someone whose main need is low-cost index investing, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: some mutual funds have minimums; platform is plainer than rivals. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- Very low-cost index funds and ETFs
- Long-term focus
- Broad fund lineup
- Some mutual funds have minimums
- Platform is plainer than rivals
Betterment
Ideal for: Automated IRA investing
Betterment manages an IRA portfolio automatically based on your goals and risk level, with rebalancing and planning tools. It suits savers who want investing handled for them rather than picking funds themselves. For someone whose main need is automated ira investing, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is See website, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: management fee applies; less control over individual picks. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- Automated portfolio management
- Goal planning
- Tax-loss harvesting on some plans
- Management fee applies
- Less control over individual picks
SoFi
Ideal for: Simple app-based IRA
SoFi offers IRAs through a simple app, with self-directed investing and automated portfolios. It suits younger savers who want a straightforward mobile experience and low fees. For someone whose main need is simple app-based ira, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: investment choice is narrower than big brokers; advice is limited. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- No account minimum
- App-based investing
- Automated portfolios available
- Investment choice is narrower than big brokers
- Advice is limited
E*TRADE
Ideal for: Education and mobile investing
E*TRADE, now part of Morgan Stanley, offers IRAs with broad investment choice and a strong education library. It suits investors who want to learn as they invest and trade from a capable mobile app. For someone whose main need is education and mobile investing, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: some funds and services carry fees; platform has many menus. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- No account minimum for many IRAs
- Strong education library
- Good mobile app
- Some funds and services carry fees
- Platform has many menus
Merrill
Ideal for: Bank-linked IRA investing
Merrill offers IRAs linked to Bank of America banking, with research and guided portfolios. It suits customers who already bank with Bank of America and want investing and banking in one relationship. For someone whose main need is bank-linked ira investing, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is Free, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: full advice costs extra; fund fees vary. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- Links to Bank of America accounts
- Research
- Guided portfolios
- Full advice costs extra
- Fund fees vary
Wealthfront
Ideal for: Automated low-cost IRA
Wealthfront manages IRA portfolios automatically with diversified ETFs and planning tools. It suits hands-off savers who want a low-cost automated plan rather than choosing individual investments. For someone whose main need is automated low-cost ira, that focus matters because it shapes the daily experience, from setup to the features you will actually use each week. On pricing, the starting point is See website, with a free option listed as Yes. That makes it worth checking the full pricing page before you commit, since the plan that looks cheapest can miss a feature you need, while a higher plan may include tools you would otherwise buy separately. The trade-off to weigh is this: management fee applies; limited individual stock control. If that trade-off does not block your main task, this option deserves a place on your shortlist, and a short trial with a real project will tell you more than any feature list.
- Automated portfolios
- Planning tools
- Tax-loss harvesting
- Management fee applies
- Limited individual stock control
How we picked these
We compared official feature pages and pricing pages, app store listings where relevant, privacy policies, and public reviews, and we only listed products that exist and work today and truly fit the topic. We mixed well-known leaders with strong smaller options, and we favoured products with clear pricing, clear free-tier terms, and a clear audience, rather than tools that try to cover every use case at once. We did not claim hands-on testing that did not happen. Instead, we weighed what each product is built for, who it fits best, what it costs to start, and where it falls short, so the pros and cons reflect real trade-offs you will meet in daily use. If a price could not be verified from an official source, we listed it as See website rather than guessing.
What to check before you choose
Compare account minimums, fund fees, and whether you want self-directed investing or automated management. Low ongoing fund fees matter more over decades than a signup offer. Check contribution limits and tax rules for your situation before you open an account, and confirm fees on the provider site. Also check support options, since help quality matters when something goes wrong at a busy moment. Look for clear documentation, a responsive support channel, and a way to export your data if you later switch. A tool that is easy to leave is often easier to trust, because you are not locked in by your own files. Finally, trial with a real task, not just a demo. Set up the exact workflow you will use, invite the people who will use it, and test on the devices you own. A week of real use reveals friction that a feature list hides, and it gives you a fair basis to compare your top two options before you pay.
Frequently asked questions
What is the best IRA company for beginners?
Fidelity and Charles Schwab are strong starting points with no minimum on many IRAs and broad education. Automated options like Betterment and Wealthfront suit beginners who want the portfolio managed for them.
What is the best Roth IRA company?
Fidelity, Schwab, and Vanguard all offer Roth IRAs with broad low-cost choice. The best pick depends on whether you want zero-expense funds, service, or a specific index fund lineup.
Do IRA companies charge fees?
Many charge no account fee and no commission on stocks and ETFs, but fund expense ratios still apply and advice services cost extra. Check the full fee schedule before you invest.
Can I have more than one IRA?
Yes, you can hold multiple IRAs, but annual contribution limits apply across all of them combined. Keep track of contributions to avoid exceeding the limit.