Best Pay Later Apps in 2026: 8 Options Compared

- Klarna and Afterpay suit everyday pay in four shopping at many stores.
- Affirm suits larger purchases with monthly terms.
- PayPal Pay in 4 suits existing PayPal users at checkout.
- Sezzle, Zip and Splitit suit shoppers who want budgeting tools, store options or card based splits.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
 Klarna | pay in instalments at many stores | Free | Free | Visit |
 Afterpay | simple pay in four for shopping | Free | Free | Visit |
 Affirm | larger purchases with monthly payments | Free | Free | Visit |
 PayPal Pay in 4 | pay later inside PayPal checkout | Free | Free | Visit |
 Sezzle | pay in four with budgeting tools | Free | Free | Visit |
 Zip | pay later in stores and online | Free | Free | Visit |
 Shop Pay Installments | pay later at Shopify stores | Free | Free | Visit |
 Splitit | split payments on an existing card | Free | Free | Visit |
The best pay later apps
We compared official feature pages, pricing, app store listings, privacy policies and public reviews for this list. The options below cover different budgets and needs, so read the best for line first and then the full write up for the products that match your situation.
Klarna
Ideal for: pay in instalments at many stores
Klarna fits pay in instalments at many stores. Its wide store coverage makes it easy to split many everyday purchases. The strengths we noted were pay in four and monthly options; wide store coverage; app for tracking payments. For many readers, that mix makes it worth a close look before deciding.
The honest catch is that users should check fees and credit effects for the specific plan they choose. Pricing is listed as Free, with a free plan status of Free. Before you commit, try the free tier or trial with your real work, and check the limits that matter for your use. That short test will tell you more than any feature list.
- Pay in four and monthly options
- Wide store coverage
- App for tracking payments
- Late fees and interest can apply on some plans
- Missed payments affect credit in some cases
Afterpay
Ideal for: simple pay in four for shopping
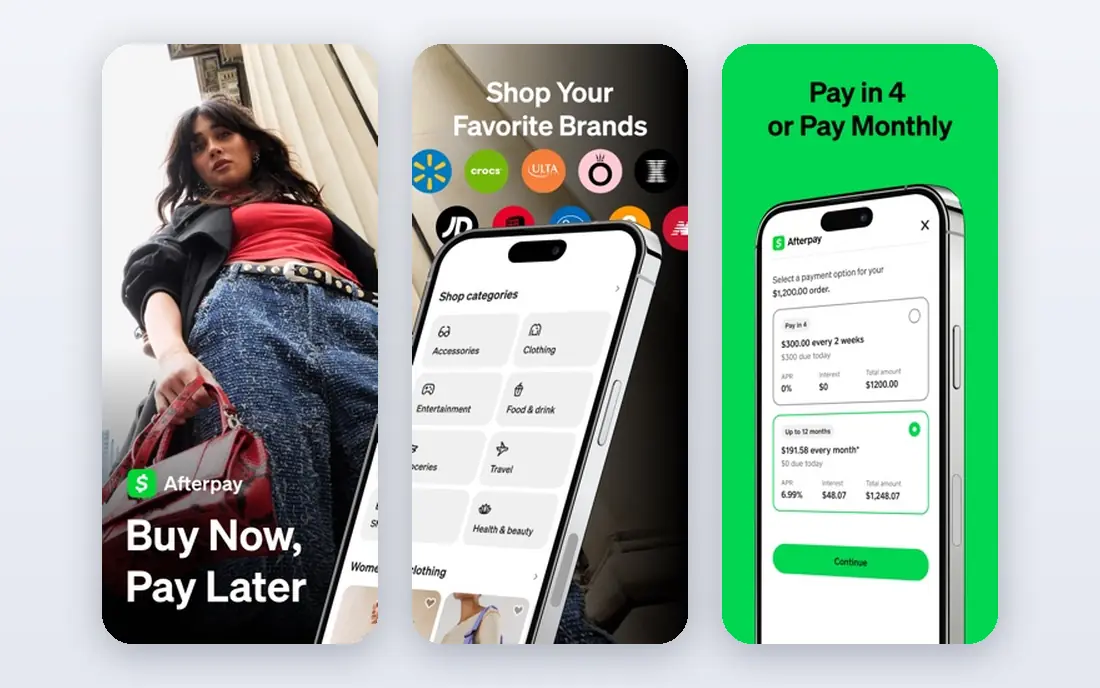
For simple pay in four for shopping, Afterpay is a natural first candidate. Its simple pay in four schedule suits shoppers who want clear, short splits. In practice, that means pay in four with clear schedules; wide retail coverage; app reminders. It is not perfect for everyone, but the fit is clear for this use.
On the downside, users should keep total Afterpay commitments low to avoid late fees. The starting price is Free, and the free plan status is Free. We suggest testing it with a real task, checking support and export options, and confirming that the plan you need covers your team or household size.
- Pay in four with clear schedules
- Wide retail coverage
- App reminders
- Late fees apply
- Spending limits depend on history
- Not for all purchase types
Affirm
Ideal for: larger purchases with monthly payments

Affirm is aimed at larger purchases with monthly payments, and the fit shows in daily use. Its upfront monthly terms suit larger purchases where a longer split makes sense. Readers who value monthly payments for larger purchases; clear interest terms upfront; many partners will see the appeal quickly.
The trade off is that shoppers should compare interest cost with saving for the purchase first. Starting price is Free, with free plan status Free. A trial with your own data is the best next step, since it reveals setup time, limits and everyday friction that a sales page hides.
- Monthly payments for larger purchases
- Clear interest terms upfront
- Many partners
- Interest can apply
- Approval depends on credit checks for some plans
PayPal Pay in 4
Ideal for: pay later inside PayPal checkout
If you need a tool for pay later inside PayPal checkout, start with PayPal Pay in 4. Its PayPal checkout integration makes pay later easy for existing PayPal users. The result is a product that covers pay in four at paypal checkout; familiar account; no interest on pay in 4 in many cases without forcing a complex setup.
Keep in mind that users should check eligibility and late fee terms for each purchase. It lists a starting price of Free and a free plan status of Free. Compare the total cost for your real use, including any add ons, before you settle on it.
- Pay in four at PayPal checkout
- Familiar account
- No interest on Pay in 4 in many cases
- Availability varies by purchase and account
- Late fees can apply
Sezzle
Ideal for: pay in four with budgeting tools
Sezzle fits pay in four with budgeting tools. Its budgeting tools help users plan splits around paydays. The strengths we noted were pay in four; budgeting and payment scheduling tools; store directory. For many readers, that mix makes it worth a close look before deciding.
The honest catch is that shoppers should still keep total split commitments within their budget. Pricing is listed as Free, with a free plan status of Free. Before you commit, try the free tier or trial with your real work, and check the limits that matter for your use. That short test will tell you more than any feature list.
- Pay in four
- Budgeting and payment scheduling tools
- Store directory
- Late fees can apply
- Limits depend on account history
Zip
Ideal for: pay later in stores and online
For pay later in stores and online, Zip is a natural first candidate. Its in store and online options suit shoppers who split purchases in both places. In practice, that means pay in four online and in store options; app for managing payments. It is not perfect for everyone, but the fit is clear for this use.
On the downside, users should check regional fees and late terms before using it. The starting price is Free, and the free plan status is Free. We suggest testing it with a real task, checking support and export options, and confirming that the plan you need covers your team or household size.
- Pay in four online and in store options
- App for managing payments
- Fees can apply depending on plan and region
- Late fees are possible
Shop Pay Installments
Ideal for: pay later at Shopify stores
Shop Pay Installments is aimed at pay later at Shopify stores, and the fit shows in daily use. Its Shopify checkout integration makes instalments fast at participating stores. Readers who value instalments at shopify checkout; quick checkout for returning users will see the appeal quickly.
The trade off is that shoppers buying outside Shopify need another pay later app. Starting price is Free, with free plan status Free. A trial with your own data is the best next step, since it reveals setup time, limits and everyday friction that a sales page hides.
- Instalments at Shopify checkout
- Quick checkout for returning users
- Availability is limited to participating Shopify stores
- Terms vary by purchase
Splitit
Ideal for: split payments on an existing card
If you need a tool for split payments on an existing card, start with Splitit. Its card based splits suit users who already have a suitable credit card. The result is a product that covers splits on an existing credit card without a new loan application in many cases; monthly plans without forcing a complex setup.
Keep in mind that users without enough available credit cannot use it for that purchase. It lists a starting price of Free and a free plan status of Free. Compare the total cost for your real use, including any add ons, before you settle on it.
- Splits on an existing credit card without a new loan application in many cases
- Monthly plans
- Requires a credit card with enough available credit
- Interest depends on the card
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews. We checked that each product exists and works today, that it truly fits the topic, and that its official homepage loads. We favoured products with clear pricing or a clear free tier, honest limits, and a distinct use case, rather than listing near duplicates.
We did not claim hands on testing that did not happen. Where pricing was quoted rather than listed, we wrote See website rather than guessing a number. Where a product had a known limit, such as a watermark on a free plan or a state limit on cover, we stated it plainly so readers can judge the trade off. Readers should also check the current plan details on the vendor site before buying, since prices and free tiers change over time.
How to choose a pay later app
Start with the purchase size. Short pay in four plans suit smaller purchases, while monthly plans suit larger ones. Do not stretch a small purchase over a long plan with interest when a short split would do.
Next, read the full cost. Check interest, late fees and credit reporting for the exact plan, not just the headline split. A plan that looks free can still carry late fees if a payment is missed.
Finally, keep total commitments in view. Multiple pay later plans across apps add up fast. Track all open splits, set reminders, and pause new splits if payments start to feel tight.
Frequently asked questions
Are pay later apps safe?
Reputable apps use clear terms and security controls, but missed payments can bring fees and credit effects. Read the plan terms and keep payments within your budget.
Do pay later apps affect credit?
Some plans involve credit checks and report missed payments, while others do not. Check the specific plan terms, since reporting varies by app and plan.
What is the best pay later app?
Klarna and Afterpay suit everyday pay in four use, while Affirm suits larger purchases. PayPal Pay in 4 suits existing PayPal users.
Can I use pay later for any purchase?
No. Availability varies by store, purchase amount and eligibility. Some purchases, such as certain services, may not qualify.
What happens if I miss a payment?
Late fees can apply, and further purchases may be blocked until the payment is made. Contact the provider early if you expect difficulty, rather than ignoring the payment.