Best tradeline companies in 2026: 7 Options Compared

- 1
 Tradeline Supplybuyers who want to browse live inventoryVisit
- 2
 Boost Credit 101buyers who want a guided consultationVisit
- 3
 Superior Tradelinesbuyers who want plain explanations of the processVisit
- 4
 Personal Tradelinesbuyers who want a tailored recommendationVisit
- 5
 Coast Tradelinesbuyers who want to see sample deals upfrontVisit
- Tradeline Supply shows live inventory with bank, limit, age and price before you buy, which makes comparison easier than a quote-only service.
- Boost Credit 101 and Personal Tradelines both offer a free consultation and a refund policy if a line does not post as agreed.
- Coast Tradelines and Priority Tradelines give longer rental windows, which can matter if your application timeline slips by a few weeks.
- No company can promise a set score rise, so treat any provider that does as a reason to walk away.
Quick comparison
| Product | Ideal for | Price from | Free version | |
|---|---|---|---|---|
| Tradeline Supply | buyers who want to browse live inventory | See website | No | Visit |
| Boost Credit 101 | buyers who want a guided consultation | See website | No | Visit |
| Superior Tradelines | buyers who want plain explanations of the process | See website | No | Visit |
| Personal Tradelines | buyers who want a tailored recommendation | See website | No | Visit |
| Coast Tradelines | buyers who want to see sample deals upfront | See website | No | Visit |
 GFS Group | buyers, brokers and sellers in one place | See website | No | Visit |
 Priority Tradelines | buyers who want a longer rental period | See website | No | Visit |
The best tradeline companies
Buying an authorized user tradeline means renting a place on a seasoned credit card account so its history can appear on your credit report. We compared official company pages, inventory listings, guarantee terms and public reviews, focusing on posting promises, transparency and support. This is not financial advice, and tradelines carry risk, since lenders may weigh authorized user accounts differently and results vary by profile.
Tradeline Supply
Ideal for: buyers who want to browse live inventory
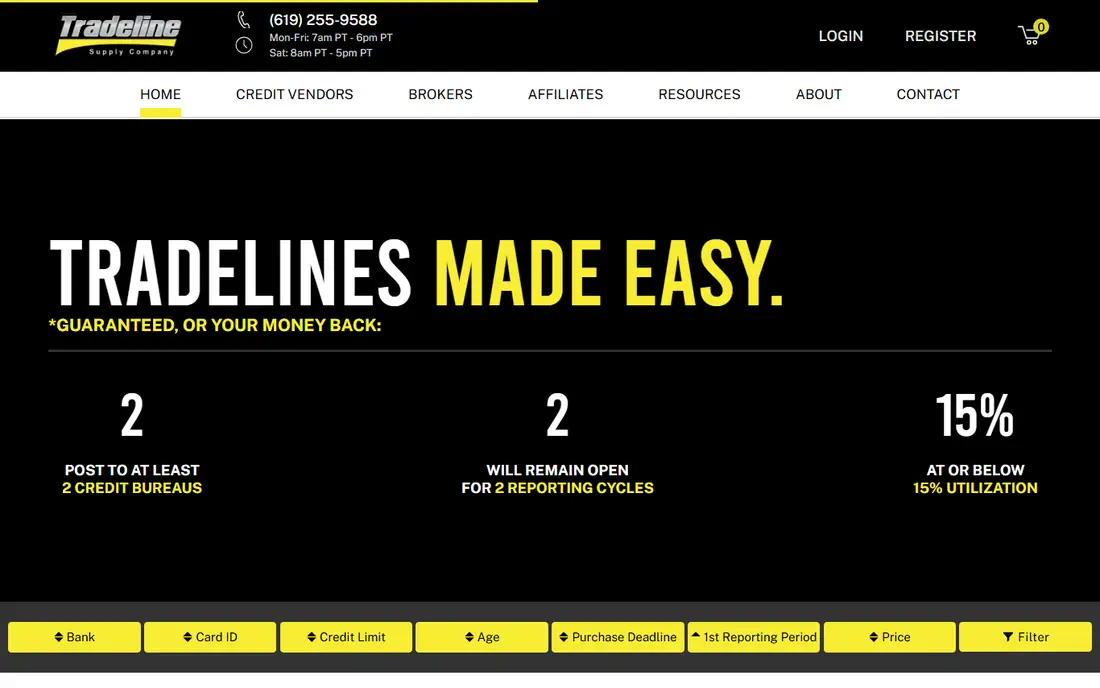
Tradeline Supply runs a marketplace style site where you can filter lines by bank, credit limit, age and price before you commit, and the listings we saw showed a first reporting window for each line. That open inventory helps you compare a younger high limit line against an older line with a lower limit, rather than accepting a single recommendation. The company also serves sellers and brokers, which keeps its inventory broad across major banks.
Before you pay, check the limits that apply to your own use, including seats, storage, monthly usage and support hours. A plan that looks generous on the headline page can still cap the one feature you rely on most, so read the plan comparison page rather than the marketing summary. A trial or free tier is the safest way to test this, and it also shows whether support answers promptly when you need help.
The trade off is choice overload and price spread, since older lines with high limits cost far more than newer ones. Check the reporting window and the guarantee terms for the exact line you pick, and confirm how a non-posting is handled before you pay, because a refund or exchange is only useful if the terms are clear.
- Live inventory with prices
- Posting guarantee
- Buyer and seller programs
- Prices vary by line
- Results are not promised
Boost Credit 101
Ideal for: buyers who want a guided consultation
Boost Credit 101 pairs each buyer with a consultant who reviews the credit report and recommends lines for a stated goal, such as preparing for a mortgage or an auto loan. The site describes posting in as little as two weeks in some cases, with an average nearer thirty days, and a refund policy if lines do not post as agreed. For first time buyers, that guided process can feel calmer than browsing a marketplace alone.
The price on the headline page is only part of the cost, so check renewal pricing, per-seat charges and any paid add-ons before you commit. Free tiers help for light use, but they often cap the features that matter once work grows, and trials end on a fixed date whether you have finished testing or not. Set a reminder before a trial ends, and confirm cancellation steps in advance so you are not locked into a plan you no longer need.
The catch is that you will not see firm prices until you talk through your case, so comparison shopping takes more calls. Ask for the total cost, the posting window and the refund terms in writing, and compare at least one marketplace price for a similar age and limit before you decide.
- Free consultation
- Refund policy
- Consultant stays involved
- Pricing is quote based
- No public price list
Superior Tradelines
Ideal for: buyers who want plain explanations of the process
Superior Tradelines explains the legal basis for authorized user accounts and the two billing cycle pattern that most rented lines follow, which helps new buyers set realistic expectations. The site is direct about the fact that a score rise cannot be promised and that the effect fades once a line stops reporting. That honesty is useful, because it frames a tradeline as a short term tool rather than a permanent fix.
Pricing is where many readers get caught out, so look past the headline figure and check what the plan actually includes for your level of use. Seats, usage limits, add-ons and renewal terms can change the real monthly cost, and a cheaper plan that lacks one feature you need is not a saving. If a free tier or trial is offered, use it for real work before paying, and confirm how cancellation works while you still have time to change your mind.
The site is less of a shopping tool than a marketplace, so you will need to contact the company to discuss inventory and prices. That extra step suits buyers who want advice, but it makes quick price comparison harder, so ask for comparable lines by age, limit and bank.
- Clear legal background
- Phone and email support
- Straightforward process
- Site is simpler than marketplace rivals
- Pricing is not listed
Personal Tradelines
Ideal for: buyers who want a tailored recommendation
Personal Tradelines builds its pitch around matching lines to your specific report, goals and timeline rather than selling a standard package. Its process runs through a consultation, a plain language agreement, reserved inventory and a joint review once lines post, with a refund policy behind the posting promise. Buyers who feel lost in a long inventory list may prefer this guided route.
Before you pay, check the limits that apply to your own use, including seats, storage, monthly usage and support hours. A plan that looks generous on the headline page can still cap the one feature you rely on most, so read the plan comparison page rather than the marketing summary. A trial or free tier is the safest way to test this, and it also shows whether support answers promptly when you need help.
The downside is the same as with other guided services, since you cannot check prices or compare lines online before the call. Keep notes from the consultation, ask how the recommended line improves on cheaper options, and confirm the posting window and refund terms before signing.
- Free consultation
- Tailored matching
- Refund policy
- Pricing is quote based
- No live inventory shown
Coast Tradelines
Ideal for: buyers who want to see sample deals upfront
Coast Tradelines shows sample deals with bank, limit, age and price, and explains that accounts often post eight to ten days after the statement date. Buyers fund a wallet and then select lines, and the site is open about the fact that Equifax posting can be less consistent than Experian and TransUnion. That candour helps you judge timing if a lender pulls a specific bureau.
The price on the headline page is only part of the cost, so check renewal pricing, per-seat charges and any paid add-ons before you commit. Free tiers help for light use, but they often cap the features that matter once work grows, and trials end on a fixed date whether you have finished testing or not. Set a reminder before a trial ends, and confirm cancellation steps in advance so you are not locked into a plan you no longer need.
The wallet step adds a layer to manage, since unused funds sit with the company until you use or reclaim them. Confirm how refunds of wallet funds work, how many lines you may hold at once, and what happens if a line posts to only one bureau.
- Sample deals with limits and prices
- Wallet funding
- Human support
- Equifax posting can be uneven
- Wallet model needs care
GFS Group
Ideal for: buyers, brokers and sellers in one place
GFS Group runs a platform for buying, selling and brokering authorized user tradelines, with a guarantee that lines will post to at least two major bureaus or be replaced or refunded. The company describes an algorithm based suggestion feature that matches lines to your goals, which can shorten the search if you know your target age and limit. Brokers who buy for clients get a structured route that consumer only sites do not offer.
Pricing is where many readers get caught out, so look past the headline figure and check what the plan actually includes for your level of use. Seats, usage limits, add-ons and renewal terms can change the real monthly cost, and a cheaper plan that lacks one feature you need is not a saving. If a free tier or trial is offered, use it for real work before paying, and confirm how cancellation works while you still have time to change your mind.
The business facing side can make the consumer journey feel less simple than a guided consultation service. Read the guarantee carefully, confirm the minimum rental period for your line, and compare the suggested line against a direct marketplace listing before paying.
- Large inventory
- Broker and seller programs
- Posting guarantee
- Platform focus can feel business oriented
- Prices vary by line
Priority Tradelines
Ideal for: buyers who want a longer rental period
Priority Tradelines rents lines for three billing cycles rather than the usual two, which gives you more time if a loan application moves slowly. The site offers order tracking, an auto matching tool based on lender, age, limit and budget, and a comparison calculator for weighing options. It also states clearly that results vary and that lenders may treat authorized user accounts differently.
Before you pay, check the limits that apply to your own use, including seats, storage, monthly usage and support hours. A plan that looks generous on the headline page can still cap the one feature you rely on most, so read the plan comparison page rather than the marketing summary. A trial or free tier is the safest way to test this, and it also shows whether support answers promptly when you need help.
You will need to supply identity documents, including a licence and Social Security card details, which is standard for this industry but still deserves care. Use a secure connection, confirm how documents are stored, and ask for the full cost and posting window in writing before you upload anything.
- Three billing cycle rentals
- Order tracking
- Secure checkout
- Identity documents required
- Pricing is quote based
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for each option in this guide. We kept only products that exist and work in October 2026 and that fit the topic directly, and we checked that each official homepage loads and belongs to the product named. Prices and free tiers are taken from the vendor site where we could verify them, and we wrote See website where a price could not be confirmed, rather than guessing. Our pick in each guide reflects fit for ordinary readers, not a claim of hands-on testing, and we note the honest limits of each option alongside its strengths.
How to choose a tradeline company without overpaying
Start with your goal and your timeline, then work backwards to the line you need. If you are preparing for a mortgage, ask your lender how authorized user accounts are treated, since some underwriting reviews discount them. Match the line to the weakness in your report, whether that is thin history, high utilization or a short average age, rather than buying the oldest or largest line on offer.
Compare at least three providers on the same terms: total price, rental length, posting window, bureaus covered and what happens if a line does not post. Keep every promise in writing, avoid any company that guarantees a score number, and never present an authorized user account as your own account on an application. A tradeline is one tool among others, and paying down balances and keeping payments on time still matter more over the long term.
Frequently asked questions
What is the best tradeline company?
There is no single best company for every buyer, since fit depends on whether you want live inventory, guided advice or a longer rental. Tradeline Supply suits browsers, Boost Credit 101 and Personal Tradelines suit guided buyers, and Priority Tradelines suits buyers who need three billing cycles. Compare total price and guarantee terms for a similar line before choosing.
How much does a tradeline cost?
Prices vary widely by the age, limit and bank behind the line, and most companies price lines individually rather than charging a flat fee. Younger or lower limit lines cost less, while older high limit lines cost far more. Ask for the total price including fees, and confirm whether a non-posting brings a refund or an exchange.
How long do tradelines stay on your report?
Most rented tradelines report for two billing cycles, while Priority Tradelines offers three, and the account may remain visible for a time after it stops actively reporting. The score effect usually fades over the following months once reporting ends. Plan any application inside the active reporting window.
Are tradelines legal?
Being added as an authorized user is a standard card feature, and regulation bars banks from limiting that feature to family members alone. That said, lender policies differ, and misrepresenting an authorized user account as your own on an application is a serious mistake. Read the provider terms and, if in doubt, ask a financial adviser.
Can a tradeline guarantee a higher credit score?
No reputable company can promise a set score rise, because scoring models, bureaus and your existing profile all affect the result. A strong line can help a thin file more than a file with recent negative marks. Treat any guaranteed number as a warning sign and look for a provider that explains the range of outcomes.